




What Is an Education Loan and How Does It Work?
What Is an Education Loan and How Does It Work?
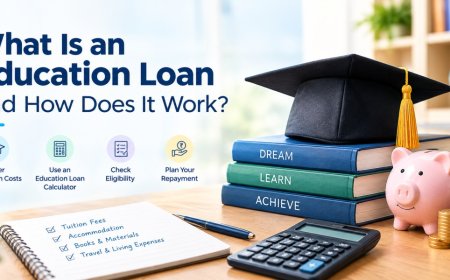
Higher education can involve substantial expenses, including tuition fees, accommodation, books, examination fees, travel, and other academic costs. For many students and families, paying these expenses entirely from savings may not be practical. An education loan can help finance eligible education-related expenses and spread the cost over a longer repayment period.
A study loan is generally designed to support students pursuing higher education in India or abroad. Depending on the loan scheme and lender, the loan may cover expenses such as course fees, hostel charges, books, equipment, and other approved costs.
Before borrowing, it is important to understand how an education loan works, how interest is charged, when repayment begins, and how much you may need to pay each month. An education loan calculator can also help estimate the EMI and overall repayment cost.
What Is an Education Loan?
An education loan is a form of financing designed to help students meet the costs associated with higher education. The loan may be used for eligible expenses related to undergraduate, postgraduate, professional, technical, or other recognized courses, depending on the lender's criteria.
Instead of paying the entire education cost upfront, the borrower receives financing according to the approved loan terms and repays the amount over an agreed period. The student is generally the primary beneficiary of the loan, while a parent or guardian may be required as a co-applicant depending on the lender's eligibility requirements.
How Does an Education Loan Work?
The basic process of an education loan usually involves several stages.
1. Choose an Eligible Course and Institution
The first step is to confirm that the course and educational institution meet the lender's requirements. Eligibility can differ depending on the type of course, institution, location, and applicable loan scheme.
2. Determine the Required Loan Amount
Students can estimate their total education expenses before deciding how much financing they need. These expenses may include:
- Tuition fees
- Hostel and accommodation expenses
- Examination fees
- Books and study materials
- Equipment required for the course
- Travel expenses in applicable cases
- Other approved education-related expenses
It is important to understand which expenses are covered before finalizing the loan amount.
3. Check Education Loan Eligibility
The lender may assess several factors when reviewing an application. These can include:
- Student's academic admission
- Course and institution
- Age and eligibility conditions
- Co-applicant details
- Income and repayment capacity
- Credit history
- Required documentation
- Collateral or security requirements, where applicable
Education loan eligibility requirements can vary, so borrowers should review the specific terms before applying.
4. Submit the Application and Documents
The applicant generally needs to provide documents related to admission, identity, address, academic records, and financial information. Depending on the loan, additional documents may be required from the co-applicant or guarantor.
5. Loan Assessment and Approval
After receiving the application, the lender evaluates the applicant and the proposed education loan. If the application meets the required conditions, the lender may approve the loan subject to its terms.
6. Disbursement
Once the necessary conditions are completed, the approved loan amount may be disbursed according to the lender's process. In many cases, education loan disbursement may be linked to the fee schedule or other eligible education expenses.
What Expenses Can an Education Loan Cover?
The expenses covered by an education loan depend on the specific loan product and lender. Common eligible expenses may include:
- Course or tuition fees
- Hostel fees
- Examination fees
- Library fees
- Books and educational materials
- Required equipment
- Certain travel expenses for overseas education
- Other approved academic expenses
Students should check the loan agreement to understand exactly what is covered.
What Is the Difference Between an Education Loan and a Study Loan?
The terms education loan and study loan are often used interchangeably when discussing financing for higher education. Both generally refer to borrowing designed to help students fund eligible education expenses.
However, the exact features can differ depending on the lender and loan product. Interest rates, loan limits, repayment tenure, collateral requirements, moratorium periods, and eligibility conditions may vary. Therefore, borrowers should compare the actual terms rather than relying only on the name of the loan.
What Is the Interest Rate on an Education Loan?
The interest rate determines the cost of borrowing. For example, if you borrow ₹10 lakh, the interest charged over the repayment period will depend on factors such as the applicable interest rate, outstanding principal, repayment schedule, and loan terms. Education loans may have fixed or floating interest-rate structures depending on the product.
A floating interest rate can change according to the applicable benchmark and the lender's terms. This can affect the repayment schedule or total interest payable.
Before taking a study loan, understand:
- Applicable interest rate
- Interest-rate type
- Benchmark or rate-reset conditions, if applicable
- Processing fees
- Other applicable charges
- Prepayment conditions
How Is Education Loan EMI Calculated?
Once repayment begins, the borrower generally makes regular instalment payments. The EMI depends primarily on:
- Principal loan amount
- Interest rate
- Repayment tenure
The standard EMI formula is:
EMI = P × R × (1 + R)ⁿ / [(1 + R)ⁿ − 1]
Here:
- P = Principal loan amount
- R = Monthly interest rate
- N = Number of monthly instalments
For example, a ₹10 lakh loan at a 10% annual interest rate for 10 years would have an estimated EMI of around ₹13,215 under a standard monthly reducing-balance calculation.
The actual repayment amount can vary depending on the lender's terms, interest calculation method, moratorium treatment, fees, and other conditions.
What Documents Are Required for an Education Loan?
The documentation requirements depend on the lender and loan type. Commonly requested documents may include:
- Proof of identity
- Proof of address
- Academic records
- Admission or offer letter
- Course fee structure
- Passport or visa-related documents for applicable overseas education
- Income documents of the co-applicant
- Bank statements
- Collateral documents, where applicable
Providing accurate and complete information can help avoid unnecessary delays in processing.
Benefits of Planning an Education Loan Before Borrowing
Proper planning can help students and families understand the financial commitment involved. Before applying, consider:
- Calculate the Total Education Cost: Estimate tuition fees and other eligible expenses to determine how much financing may actually be required.
- Check Your Repayment Capacity: Consider potential future income and other financial commitments before selecting a loan amount and tenure.
- Compare Loan Terms: Look beyond the interest rate. Check processing fees, repayment conditions, moratorium terms, collateral requirements, and other applicable charges.
- Calculate the EMI: Use an education loan calculator to estimate the monthly repayment under different loan amounts and tenures.
- Avoid Unnecessary Borrowing: Borrowing only what is required for eligible education expenses can help keep the overall repayment obligation manageable.
Final Thoughts
An education loan can help students and families manage the cost of higher education by spreading eligible expenses over a structured repayment period. However, borrowing should be planned carefully. Before taking a study loan, understand the loan amount, interest rate, repayment tenure, moratorium period, eligibility requirements, and collateral conditions.
What's Your Reaction?