





UK Fintech Lending Market Size, Share, Trends, Growth & Forecast Report 2026-2034
The UK fintech lending market grew from USD 16.2 Billion in 2025 to USD 18.7 Billion in 2026. Looking forward, IMARC Group expects the market to reach USD 46.6 Billion by 2034, exhibiting a growth rate (CAGR) of 12.12%
Market Overview
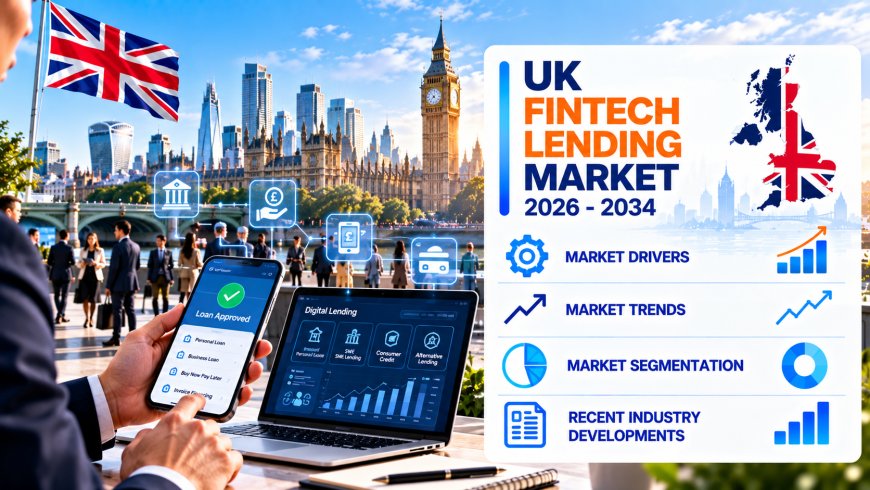
The UK fintech lending market size reached USD 16.2 Billion in 2025, grew to USD 18.7 Billion in 2026, and is projected to reach USD 46.6 Billion by 2034, growing at a compound annual growth rate (CAGR) of 12.12% from 2026 to 2034. The market is driven by digital adoption, AI-based credit assessment, open banking, supportive regulation, and demand for small business loans.
UK Fintech Lending Market Summary
- The UK fintech lending market covers technology-based lending to individuals and businesses, including peer-to-peer, marketplace, direct, and crowdfunding models.
- Fintech lending is valued for faster decisions, lower operating costs, and access to credit for borrowers that banks may underserve.
- The ecosystem includes fintech lenders and platforms, banks and funders, investors, data and technology providers, regulators, small businesses, and consumers.
- Major segments identified in the market include service type (consumer, small business, real estate lending), business model (P2P, marketplace, direct, crowdfunding, hybrid), technology type (AI and ML, blockchain, mobile, big data analytics), end user, and region. IMARC does not give shares for these.
- Open Banking, introduced in 2019, lets fintechs access bank data with customer consent, and FCA sandboxes allow firms to test products under controlled conditions.
- IMARC does not describe restraints or challenges on the page.
Request a Sample Report for In-Depth Market Insights: https://www.imarcgroup.com/uk-fintech-lending-market/requestsample
PORTER’S FIVE FORCES ANALYSIS
- Competitive Rivalry: High. Fintech lenders, challenger banks, and traditional banks compete on speed, rates, and customer experience. Business implication: Differentiate through data-driven underwriting and service.
- Supplier Power (Funding and Data): Moderate to High. Fintech lenders depend on funding partners, investors, and data providers, and funding costs affect margins. Business implication: Diversify funding sources.
- Buyer Power (Borrowers): Moderate to High. Borrowers can compare offers online and switch easily. Business implication: Compete on transparency, speed, and tailored products.
- Threat of Substitutes: Moderate. Bank loans, credit cards, overdrafts, and buy now pay later offers substitute for fintech loans. Business implication: Position on convenience and underserved segments.
- Threat of New Entrants: Moderate. Technology lowers entry barriers, but authorisation, funding, and credit risk management are hurdles. Business implication: Build strong risk models and compliance capability.
MARKET GROWTH DRIVERS
Digital Adoption and Streamlined Lending
Digital-first preferences, particularly among millennials and Gen Z, are increasing demand for online credit. Streamlined application procedures and lower operating costs let fintech lenders approve loans faster than banks. Post-COVID-19 demand for flexible credit further strengthened the move toward digital lenders.
AI, Data, and Open Banking
Artificial intelligence and machine learning improve credit assessment, using non-traditional data such as payment history and behavioral patterns. Open Banking gives fintechs access to bank data with customer consent, while blockchain supports secure, transparent processing. Data-driven risk models help lenders price loans more precisely.
SME Demand and Supportive Regulation
Small businesses are turning to fintech lenders as banks impose stricter standards and slower approvals, raising demand for small business loans. Favorable regulatory support, including FCA regulatory sandboxes that let firms test products in controlled conditions, helps new lenders launch and scale products.
UK FINTECH LENDING MARKET SEGMENTATION
Service Type Insights:
- Consumer Lending
- Small Business Lending
- Real Estate Lending
Business Model Insights:
- Peer-to-Peer (P2P) Lending
- Marketplace Lending
- Direct Lending
- Crowdfunding
- Hybrid Models
Technology Type Insights:
- AI and ML
- Blockchain
- Mobile Technology
- Big Data Analytics
End-User Insights:
- Individuals
- Businesses
Regional Insights:
- London
- South East
- North West
- East of England
- South West
- Scotland
- West Midlands
- Yorkshire and The Humber
- East Midlands
- Others
COMPETITIVE LANDSCAPE
The UK fintech lending market includes digital lenders, peer-to-peer and marketplace platforms, challenger banks, and technology providers. IMARC says the report includes a competitive dashboard and evaluation quadrant but names no companies on the page. Competition centers on credit assessment quality, speed, pricing, funding access, and customer experience.
Key organizations mentioned in the report's context include:
- Abound raised £800 million in May 2025 for its AI-based lending platform, Render, which uses bank transaction data to assess how much customers can borrow.
REGIONAL ANALYSIS
- London: The main fintech hub, with concentrated talent, funding, and lenders.
- South East: Strong links to London and a large base of consumers and small businesses.
- North West, Yorkshire and The Humber, West Midlands, and East Midlands: Established business centers with growing demand for small business and consumer credit.
- Scotland, East of England, South West, and Others: Growing digital adoption and local business demand.
RECENT INDUSTRY DEVELOPMENTS
October 2026: UK fintech lenders adapt to new Buy Now, Pay Later regulations. The Financial Conduct Authority began regulating third-party Buy Now, Pay Later credit agreements on 15 July 2026. Providers must meet relevant authorisation requirements, conduct affordability assessments and give consumers clearer borrowing information. The changes create additional compliance requirements while strengthening consumer protection across digital lending platforms.
September 2026: Financial Conduct Authority outlines measures to improve small-business access to finance. The regulator identified barriers including complex applications, duplicated checks and limited awareness of funding options. Microbusinesses account for 95.5% of UK small and medium-sized enterprises, and are particularly likely to face difficulties accessing suitable finance. The FCA plans to reduce friction through regulatory reform and better information for borrowers.
October 2026: DECTA and SAPI launch payment-linked financing for UK small businesses. The new DECTA Capital product allows eligible merchants to access working capital within their existing payment systems, with offers typically available within 24 hours. Repayments are linked to card-sales volumes rather than fixed monthly instalments, offering businesses a more flexible way to manage cash flow.
Key Aspects Required for the UK Fintech Lending Market
- Market Performance: USD 16.2 Billion in 2025 and USD 18.7 Billion in 2026, with a projected trajectory to USD 46.6 Billion by 2034.
- Market Outlook: A 12.12% CAGR through 2034 indicates strong growth.
- Growth Drivers: Digital adoption and streamlined lending; AI, data, and open banking; and SME demand with supportive regulation.
- Competitive Landscape: Digital lenders, P2P and marketplace platforms, challenger banks, and technology providers competing on credit quality, speed, and pricing.
- Value Chain Analysis: From funders and data providers, through lending platforms, to consumers and small businesses.
- Industry Trends: AI-based underwriting; open banking data; alternative lender adoption; and regulatory oversight of newer credit products.
- Strategic Recommendations: Invest in AI credit models; diversify funding; use open banking data; and build compliance for new rules.
Note: If you need any specific information that is not currently covered within the scope of the report, we will provide the same as a part of customization.
Speak to an analyst: https://www.imarcgroup.com/request?type=report&id=25435&flag=C
Report Format, Delivery, and Customization Details
- Report Format Mode: PDF and Excel (Editable version in PPT/Word format available on special request)
- Report Delivery Mode: Online Delivery, Physical Delivery
- Report Delivery Time: report delivered over email within 24 to 48 hours. If requested by the client, a physical copy will be delivered within three to ten days.
- Report Confirmation Mode: Yes, via email
- Report Customization Mode: Yes, via Email / Call
- Report Table of Content: Yes
- Report List of Figures: Yes
- Report Methodology Mode: Yes
- Request For Sample Report: Yes
What's Your Reaction?