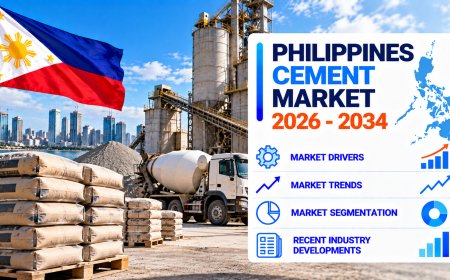




Philippines Cement Market Analysis Report 2026-2034
The Philippines cement market size was valued at USD 1.7 Billion in 2025 and is projected to reach USD 2.7 Billion by 2034, at a CAGR of 4.80%.
Market Overview
The Philippines cement market size reached USD 1.7 Billion in 2025 and is projected to reach USD 2.7 Billion by 2034, growing at a compound annual growth rate (CAGR) of 4.80% from 2026 to 2034. The market is driven by government infrastructure spending, urbanization and housing demand, industrial zones and foreign investment, and sustainable cement adoption.
Philippines Cement Market Summary
- The Philippines cement market covers blended, Portland, and other cement types used in infrastructure, residential, and commercial construction.
- Cement is valued as the core building material for roads, housing, ports, and industrial facilities in a fast-urbanizing economy.
- The ecosystem includes local and foreign-invested cement producers, quarry and fuel suppliers, importers and traders, distributors and hardware retailers, contractors and developers, government agencies, and regulators.
- Major segments identified in the market include type (blended 56.8%), end use (infrastructure 42.5%), and region (Luzon 65.5%), based on 2025.
- IMARC cites Taiheiyo Cement Philippines’ San Fernando, Cebu plant, which has a capacity of three million tons a year.
- Restraints include high energy costs, import competition, quarry permitting complexity, and supply chain risk.
Request a Sample Report for In-Depth Market Insights: https://www.imarcgroup.com/philippines-cement-market/requestsample
PORTER’S FIVE FORCES ANALYSIS
- Competitive Rivalry: Moderate to High. A handful of local and foreign-invested producers compete with imports on price, reach, and product range. Business implication: Focus on cost efficiency, blended products, and distribution strength.
- Supplier Power (Energy and Raw Materials): Moderate to High. Coal and electricity are major costs, and quarry access and permits limit raw materials. Business implication: Use alternative fuels and secure long-term quarry rights.
- Buyer Power (Contractors and Distributors): Moderate to High. Large contractors and distributors buy in volume, and price-sensitive buyers can switch to imports. Business implication: Build service, brand, and delivery reliability.
- Threat of Substitutes: Low. Few materials replace cement in structural uses, though steel and timber compete in some applications. Business implication: Highlight durability and cost.
- Threat of New Entrants: Low to Moderate. Capital, permits, and scale limit local entry, but importers can enter easily. Business implication: Use safeguards and local presence to defend market position.
MARKET GROWTH DRIVERS
Infrastructure Spending
The government’s Build Better More program funds transport, water, energy, and digital projects, with the Department of Public Works and Highways receiving a major share of the budget. This steady pipeline of roads, bridges, ports, and flood control works underpins cement demand and favors producers with strong national distribution.
Urbanization, Housing, and Industrial Zones
A rising urban population, a growing middle class, and the housing backlog support residential construction, with housing programs extending demand to areas such as Davao, Iloilo, and Baguio. New industrial estates and economic zones, supported by foreign investment in manufacturing, logistics, and technology, add demand for commercial and industrial building.
Sustainability and Trade Protection
Blended and low-carbon cement is gaining ground under green building rules, while waste co-processing and alternative fuels cut fuel costs and help meet environmental requirements. IMARC’s outlook expects safeguard tariffs on imports to help rationalize domestic production, supporting local producers against low-priced imports.
PHILIPPINES CEMENT MARKET SEGMENTATION
Type Insights:
- Blended, 56.8% in 2025
- Portland
- Others
End Use Insights:
- Infrastructure, 42.5% in 2025
- Residential
- Commercial
Regional Insights:
- Luzon, 65.5% in 2025
- Visayas
- Mindanao
COMPETITIVE LANDSCAPE
The Philippines cement market includes local and foreign-invested producers alongside imports, mainly from Vietnam and Indonesia, per IMARC. IMARC names Holcim Philippines and Taiheiyo Cement Philippines and gives no ratings or rankings. Competition centers on price, product range, plant capacity, energy costs, and distribution coverage.
Key players mentioned in the report context include:
- Holcim Philippines launched Holcim Optima in June 2023, a blended Portland limestone cement with about 10% lower CO2 emissions than ordinary Portland cement.
- Taiheiyo Cement Philippines opened a PHP 12.8 billion production line in San Fernando, Cebu in July 2024, raising capacity to three million tons per year and expected to cut CO2 emissions by over 10%.
REGIONAL ANALYSIS
- Luzon: The dominant region with 65.5% of the market in 2025, with concentrated construction activity in Metro Manila, Central Luzon, and Calabarzon, and major transport, flood control, and port projects.
- Visayas: A growing region, with Cebu’s industrial and building activity, including Taiheiyo’s plant.
- Mindanao: An emerging region where housing and infrastructure demand is growing, though quarry permitting and logistics add challenges.
RECENT INDUSTRY DEVELOPMENTS
October 2026: Cement shipments from Vietnam to the Philippines decline sharply. Vietnam exported 256,350 metric tonnes of cement and clinker to the Philippines in September 2026, down 44.5% year-on-year. Shipments during January–September reached 1.99 million tonnes, declining 58.5%, potentially affecting import availability and competition for domestic cement producers.
October 2026: Philippine cement wholesale prices increase by 2.5% year-on-year. The Philippine Statistics Authority reported that the cement component of Metro Manila’s Construction Materials Wholesale Price Index recorded 2.5% annual growth in September 2026, compared with 1.9% in August. The increase reflects continuing price pressures in construction materials and affects building contractors, developers and cement distributors.
July 2026: Philippines launches a cement and concrete decarbonisation roadmap. The Board of Investments became the lead implementing agency for the national roadmap, formally handed over on 29 June. The initiative promotes low-carbon production, circular-economy technologies and improved manufacturing efficiency, while the 2026 Strategic Investment Priority Plan continues to recognise cement manufacturing as a preferred investment activity.
Key Aspects Required for the Philippines Cement Market
- Market Performance: USD 1.7 Billion in 2025, with a projected trajectory to USD 2.7 Billion by 2034.
- Market Outlook: A 4.80% CAGR through 2034 indicates steady growth.
- Growth Drivers: Infrastructure spending; urbanization, housing, and industrial zones; and sustainability and trade protection.
- Competitive Landscape: Local and foreign-invested producers competing with imports on price, range, and distribution.
- Value Chain Analysis: From quarry and fuel suppliers, through cement producers and importers, to distributors, contractors, and developers.
- Industry Trends: Blended and low-carbon cement; alternative fuels; safeguard measures on imports; and capacity upgrades.
- Strategic Recommendations: Grow blended product lines; cut energy costs through alternative fuels; defend share against imports; and secure quarry permits.
Note: If you need any specific information that is not currently covered within the scope of the report, we will provide the same as a part of customization.
Speak to an analyst: https://www.imarcgroup.com/request?type=report&id=37574&flag=C
Report Format, Delivery, and Customization Details
- Report Format Mode: PDF and Excel (Editable version in PPT/Word format available on special request)
- Report Delivery Mode: Online Delivery, Physical Delivery
- Report Delivery Time: report delivered over email within 24 to 48 hours. If requested by the client, a physical copy will be delivered within three to ten days.
- Report Confirmation Mode: Yes, via email
- Report Customization Mode: Yes, via Email / Call
- Report Table of Content: Yes
- Report List of Figures: Yes
- Report Methodology Mode: Yes
- Request For Sample Report: Yes
What's Your Reaction?