



Germany Logistics & Supply Chain Market Size, Share, Trends and Report 2034
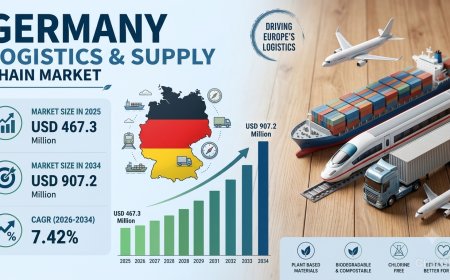
The Germany logistics & supply chain market size reached USD 467.3 Million in 2025. Looking forward, IMARC Group expects the market to reach USD 907.2 Million by 2034, exhibiting a growth rate (CAGR) of 7.42% during 2026-2034.
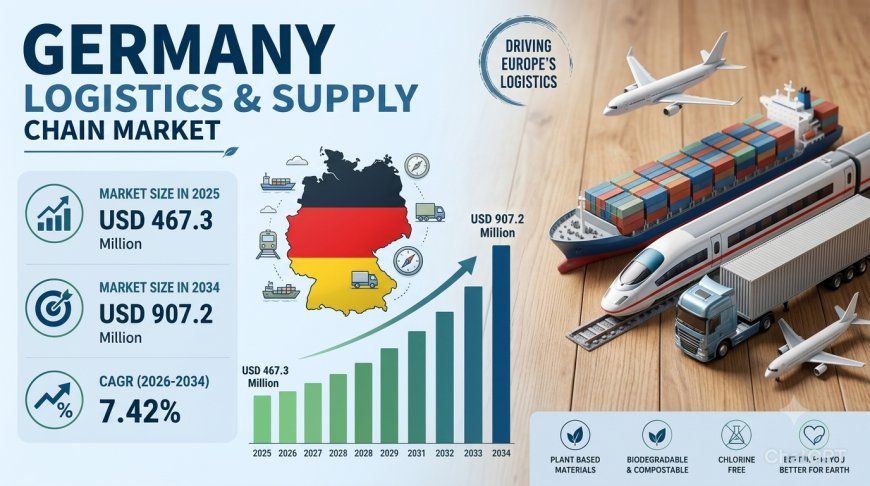
The Germany logistics & supply chain market is witnessing strong growth, driven by rapid digital transformation, the adoption of Industry 4.0 technologies, and a firm national and European commitment to sustainability. The market size reached USD 467.3 Million in 2025 and is projected to reach USD 907.2 Million by 2034, exhibiting a compound annual growth rate (CAGR) of 7.42% during 2026-2034. The widespread use of AI, IoT, predictive analytics, blockchain, and robotics for real-time tracking, route optimization, and warehouse automation, together with major investments such as Amazon's €10 billion commitment in Germany and the €1 billion fund to secure critical raw materials, is creating robust demand for modern, efficient, and low-emission logistics solutions across the country. This market is strategically important to Germany's economy as it connects manufacturers, retailers, healthcare providers, and public utilities with customers at home and across Europe.
The Germany logistics & supply chain market is poised for sustained expansion, driven by digitalization, automation, and sustainability-led investment. With a projected CAGR of 7.42% through 2034 and the market expected to nearly double from USD 467.3 Million in 2025 to USD 907.2 Million by 2034, the market presents significant opportunities for established logistics providers, technology vendors, and new entrants focused on smart, connected, and green supply chain solutions.
GERMANY LOGISTICS & SUPPLY CHAIN MARKET SUMMARY
- Market Scope: The Germany logistics & supply chain market encompasses the transportation, warehousing, sourcing and procurement, and related services that move goods and information from suppliers to end customers across Germany.
- Ecosystem: The ecosystem includes transport operators across rail, road, air, and waterways; warehousing and fulfillment providers; procurement and sourcing specialists; technology and automation vendors; and end users spanning industry, retail, healthcare, and more.
- Major Segments: The market is segmented by transportation mode (railways, roadways, airways, and waterways), application (transportation, warehousing, sourcing and procurement, and others), and end user (industry and manufacturing, retail, healthcare, aerospace, BFSI, government and public utilities, media and entertainment, food and beverages, and others).
- Market Size and Forecast: USD 467.3 Million in 2025, with a projected rise to USD 907.2 Million by 2034 at a CAGR of 7.42% during 2026-2034.
- Regional Coverage: The market is analyzed across Western Germany, Southern Germany, Eastern Germany, and Northern Germany.
- Study Period: Base year 2025; historical period 2020-2025; forecast period 2026-2034; values in USD Million.
PORTER'S FIVE FORCES ANALYSIS – GERMANY LOGISTICS & SUPPLY CHAIN MARKET
The competitive dynamics of the Germany logistics & supply chain market can be analyzed using Porter's Five Forces framework.
Porter's Five Forces Analysis – Germany Logistics & Supply Chain Market
- Competitive Rivalry: Moderate to High, with global integrators, specialist carriers, and technology-led challengers competing on service quality, speed, digital visibility, and sustainability credentials. Rivalry is driven by rising e-commerce volumes, automation investment, and expanding fulfillment networks. Business implication: Providers must differentiate through technology-enabled services, reliable end-to-end performance, and green logistics offerings to win and retain long-term contracts.
- Supplier Power (Technology, Equipment, and Fleet Providers): Moderate. Suppliers of automation systems, robotics, telematics, and alternative-fuel vehicles hold meaningful influence as demand for advanced solutions grows, yet a widening vendor base keeps options open for buyers. Business implication: Logistics operators should build strategic partnerships and diversified sourcing for technology and fleet assets to secure innovation access and favorable terms.
- Buyer Power (Shippers and Enterprise Customers): Moderate to High. Industry, retail, healthcare, and food and beverage customers increasingly seek real-time tracking, flexible capacity, and sustainable delivery options. Business implication: Providers must offer integrated, data-driven, and transparent services that deepen customer relationships and support multi-year agreements.
- Threat of Substitutes: Low to Moderate. Multimodal options across rail, road, air, and waterways, along with in-house logistics models and digital freight platforms, offer alternatives, but the need for scale, network reach, and compliance expertise keeps professional logistics services essential. Business implication: Operators should highlight multimodal flexibility, end-to-end visibility, and value-added services to stay the preferred choice.
- Threat of New Entrants: Moderate. Capital requirements for fleets, warehouses, and automation create barriers for large-scale operations, while digital platforms and niche services lower barriers for specialized entrants. Germany's growing, innovation-led market attracts new domestic and international players. Business implication: Established players should build defensible positions through network density, technology investment, and sustainable operations.
Competitive Rivalry – Moderate to High (Healthy)
- Competition spans large-scale investors and fulfillment network builders such as Amazon, equipment and automation innovators such as Jungheinrich, and retail logistics adopters piloting clean transport such as EDEKA Nord – driving differentiation through innovation, automation, and sustainability credentials rather than destructive price competition.
- Amazon's €10 billion investment in Germany (June 2024), Jungheinrich's launch of Uplift Ventures (2025), and EDEKA Nord's green hydrogen truck pilot (2025) reflect active strategic investment that is strengthening the overall market ecosystem.
Request for Sample Report: https://www.imarcgroup.com/germany-logistics-supply-chain-market/requestsample
MARKET GROWTH DRIVERS: Digitalization and Industry 4.0
Several key factors are propelling the expansion of the Germany logistics & supply chain market. Digitalization and Industry 4.0 serve as a powerful demand driver. The adoption of AI, IoT, predictive analytics, blockchain, and robotics is enabling real-time tracking, route optimization, and warehouse automation, helping companies cut costs, improve accuracy, and respond faster to customer needs. Strong investment momentum reinforces this shift, as shown by Amazon's €10 billion investment in Germany covering three new fulfillment centers, cloud infrastructure, and R&D (June 2024), and by Jungheinrich's Uplift Ventures corporate venture capital unit, which backs robotics, AI-based supply chain optimization, autonomous logistics, and sustainable energy (2025). Additionally, the expansion of fulfillment and warehousing capacity supports growth across e-commerce, retail, and manufacturing supply chains.
MARKET GROWTH DRIVERS: Sustainability and Regulation
The Germany logistics & supply chain market is also benefiting from accelerating sustainability-led transformation and supportive policy. National and EU regulations are encouraging companies to reduce emissions, adopt electric or alternative-fuel vehicles, build circular supply chains, and expand reverse logistics, opening new service categories and investment opportunities. Clean transport pilots, such as EDEKA Nord's use of green hydrogen-fueled Hyundai XCient Fuel Cell trucks for store deliveries with a stated range of up to 400 km (2025), show how operators are turning sustainability goals into practical solutions. Furthermore, supply chain resilience initiatives, including the €1 billion fund launched in September 2024 to secure critical raw materials through mining, processing, and recycling, are strengthening the foundation for dependable sourcing and procurement across German industry.
GERMANY LOGISTICS & SUPPLY CHAIN MARKET SEGMENTATION
Segmentation analysis provides a detailed view of the Germany logistics & supply chain market by category:
- Transportation Mode Insights: Railways, Roadways, Airways, Waterways.
- Application Insights: Transportation, Warehousing, Sourcing and Procurement, Others.
- End User Insights: Industry and Manufacturing, Retail, Healthcare, Aerospace, BFSI, Government and Public Utilities, Media and Entertainment, Food and Beverages, Others.
- Regional Insights: Western Germany, Southern Germany, Eastern Germany, Northern Germany.
COMPETITIVE LANDSCAPE
The Germany logistics & supply chain market features a dynamic and innovation-driven competitive landscape, with large global investors, equipment and automation specialists, and retail logistics leaders all shaping the market. Key companies highlighted in recent industry activity include:
- Amazon
- Jungheinrich
- EDEKA Nord
Strategic developments are shaping the competitive arena, notably Amazon's €10 billion investment in Germany (June 2024) covering three new fulfillment centers, cloud infrastructure, and R&D; Jungheinrich's Uplift Ventures corporate venture capital unit (2025), focused on robotics, AI-based supply chain optimization, autonomous logistics, and sustainable energy; and EDEKA Nord's pilot of green hydrogen-fueled Hyundai XCient Fuel Cell trucks (2025) for store deliveries. The full report provides a detailed competitive landscape and company profiles.
REGIONAL ANALYSIS:
Regional dynamics within the Germany logistics & supply chain market are shaped by industrial concentration, infrastructure, and consumer demand. The market is analyzed across four key regions:
- Western Germany: A densely connected industrial and consumer region where strong road, rail, and inland waterway links support high-volume transportation and distribution activity.
- Southern Germany: A leading hub for advanced manufacturing and technology-driven industries, generating steady demand for precision supply chains, warehousing, and sourcing and procurement services.
- Eastern Germany: An emerging growth region where new fulfillment, warehousing, and industrial investment are expanding logistics capacity and creating fresh opportunities for service providers.
- Northern Germany: A gateway region supported by waterways and port-linked trade flows, strengthening multimodal connectivity and the movement of goods across Germany and Europe.
RECENT INDUSTRY DEVELOPMENTS
2025: Jungheinrich launched Uplift Ventures, a corporate venture capital unit investing in robotics, AI-based supply chain optimization, autonomous logistics, and sustainable energy.
2025: EDEKA Nord began a pilot of green hydrogen-fueled Hyundai XCient Fuel Cell trucks for store deliveries, with a stated range of up to 400 km.
September 2024: Germany launched a €1 billion fund to secure critical raw materials through mining, processing, and recycling.
June 2024: Amazon announced a €10 billion investment in Germany covering three new fulfillment centers, cloud infrastructure, and R&D.
Key Aspects Required for the Germany Logistics & Supply Chain Market
- Market Performance: USD 467.3 Million in 2025, with a projected trajectory to USD 907.2 Million by 2034.
- Market Outlook: A 7.42% CAGR during 2026-2034 indicates robust growth across railways, roadways, airways, and waterways, and across transportation, warehousing, and sourcing and procurement applications.
- Growth Drivers: Digitalization and Industry 4.0 adoption (AI, IoT, predictive analytics, blockchain, robotics); national and EU sustainability regulation encouraging electric and alternative-fuel fleets, circular supply chains, and reverse logistics; and large-scale investment in fulfillment, automation, and raw material security.
- Competitive Landscape: An innovation-led landscape featuring large fulfillment investors such as Amazon, automation and venture-backed innovators such as Jungheinrich, and retail logistics adopters such as EDEKA Nord.
- Value Chain Analysis: From sourcing and procurement of materials and goods through transportation across rail, road, air, and waterways, warehousing and fulfillment, and final delivery to industry, retail, healthcare, and other end users, including reverse logistics.
- Industry Trends: Real-time tracking and route optimization; warehouse automation and robotics; hydrogen and electric fleet pilots; circular supply chains and reverse logistics; corporate venture investment in supply chain technology.
- Strategic Recommendations: Invest in digital and automation capabilities, pilot and scale low-emission transport, strengthen sourcing and procurement resilience, build partnerships with technology innovators, and target high-growth end users across Germany's four regions.
Note: If you need any specific information that is not covered currently within the scope of the report, we will provide the same as a part of customization.
Request Customization: https://www.imarcgroup.com/request?type=report&id=34820&flag=E
- Report Format, Delivery, and Customization Details
- Report Format Mode: PPT, PDF, and Excel
- Report Delivery Mode: Online Delivery, Physical Delivery
- Report Delivery Time: Report Delivered Over Email within 24 to 48 hours. If requested by the client, a physical copy will be delivered within three to ten days.
- Report Confirmation Mode: Yes via Email
- Report Customization Mode: Yes via Email / Call
- Report Table of Content: Yes
- Report List of Figures: Yes
- Report Methodology Mode: Yes
- Request For Sample Report: Yes
What's Your Reaction?