Low Tax Countries in Europe: 10 Best Options for UK High Earners in 2026

Discover 10 low tax countries in Europe for UK high earners in 2026. Compare tax residency, income tax, dividends, capital gains and relocation rules.
Sep 21, 2026 - 13:58
 0
Low Tax Countries in Europe: 10 Best Options for UK High Earners in 2026

For a UK high earner, moving to another European country can materially change the way employment income, business profits, dividends, investments and capital gains are taxed. But the important word is planning.

A low headline tax rate does not automatically mean a lower overall tax bill. Your result can depend on UK tax residency, the tax rules of the destination country, where your income arises, how your business is structured, your property interests and whether you genuinely establish your new residence.

This updated 2026 guide explores ten European jurisdictions that UK high earners may consider when researching Low Tax Countries in Europe. The list is not a ranking by tax rate. Each country uses a different model, so suitability depends heavily on your personal circumstances.

The UK itself continues to have comparatively high marginal rates. For 2026/27, the additional rate of income tax remains 45% in England, Wales and Northern Ireland, while Scotland has a top income tax rate of 48%. Dividend rates above the £500 dividend allowance are 10.75%, 35.75% and 39.35% across the relevant bands.

That helps explain why tax-efficient relocation remains an important subject for entrepreneurs, investors, senior professionals and internationally mobile families.

What Should UK High Earners Look For?

When comparing low tax countries in Europe, do not look at personal income tax alone.

A proper international tax planning review should consider:

Personal income tax: How employment, consultancy and self-employed earnings are taxed.

Dividend taxation: Particularly important for company owners extracting profits.

Capital gains tax: Essential for investors and anyone considering a business sale.

Foreign income rules: Some jurisdictions use residence-based taxation, while others provide remittance-based or specialised exemptions.

Corporate tax: Crucial when your wealth is generated through a company.

Social contributions: A headline income tax rate can look attractive until employment or social-security charges are added.

Tax residency: You must establish residence in the new country while correctly managing your UK position.

Double taxation agreements: Treaties can affect how income and gains are allocated between countries.

Recent online expat discussions reinforce one recurring issue: people often confuse having a residence permit, a tax number or a company registration with actually becoming tax resident. Those are separate concepts.

1. Monaco

Monaco remains one of the most unusual tax-friendly countries in Europe for wealthy individuals.

For most residents, Monaco does not impose personal income tax. There is also no general personal wealth tax. French nationals are the major exception because of the France-Monaco tax arrangements.

That makes Monaco tax residency particularly relevant to individuals whose income comes from investments, business interests or other sources outside the principality.

However, "no personal income tax" should never be interpreted as "no taxes at all". Monaco has VAT, social-security costs for employees and business taxes that can apply to certain companies. Residency also requires genuine accommodation and sufficient financial resources.

For a UK entrepreneur, the major attraction is therefore the potential personal tax environment, not the creation of a paper address.

2. Switzerland

Switzerland is another country that deserves attention in European tax planning, although its system is more complicated than a simple low-rate comparison suggests.

Swiss residents can face federal, cantonal and municipal taxes, meaning your precise location matters. Tax rates can vary significantly between cantons and municipalities.

Switzerland also has a special expenditure-based taxation system in some cantons for qualifying foreign nationals who meet the relevant conditions and are not working in Switzerland. This regime is based on expenditure rather than simply applying ordinary taxation to worldwide income.

Another important feature is the treatment of private investment gains. Private capital gains on movable assets such as shares are generally tax exempt when the individual is treated as a private investor rather than a professional securities dealer. Swiss real-estate gains are treated differently.

This can make Switzerland particularly relevant to high net worth individuals, portfolio investors and families whose wealth is primarily investment based.

3. Cyprus

Cyprus has become one of the most frequently discussed low tax countries in Europe for UK residents because of its tax residency framework and non-domicile rules.

Cyprus uses both a 183-day and a qualifying 60-day residence rule. Under the 60-day rule, several conditions must be satisfied, including spending at least 60 days in Cyprus, not being tax resident elsewhere, carrying on qualifying business or employment activity in Cyprus, and maintaining a permanent home there.

Cyprus changed its tax rates from 1 January 2026. The top personal income tax rate remains 35%, while the bands were revised.

The more interesting point for many entrepreneurs is the Cyprus non-dom regime. A person who is Cyprus tax resident but not domiciled for Special Defence Contribution purposes can be exempt from SDC on dividends and interest. The domicile rules are themselves detailed, with the 17-out-of-20-years rule being particularly important.

Cyprus also increased its standard corporation tax rate from 12.5% to 15% from 1 January 2026.

For a UK business owner, the combination of Cyprus tax residency, company structuring and dividend planning can therefore be significant.

4. Malta

Malta remains relevant because of its remittance basis taxation and its position within the European Union.

A person who is ordinarily resident in Malta but not domiciled there is generally taxed on Malta-source income and on foreign income remitted to Malta. Certain foreign capital gains arising outside Malta can receive different treatment and may not become taxable simply because they are received in Malta.

Malta's ordinary personal tax system is progressive, with a top rate of 35% in 2026. This means Malta should not be described as universally tax free.

Special residence programmes can provide a 15% rate on qualifying foreign-source income remitted to Malta, subject to the specific programme conditions and minimum tax obligations.

This is especially relevant for individuals with significant foreign income, investment portfolios or internationally held assets.

Recent online discussions about Malta show strong interest in the country's changing expatriate and digital-nomad tax rules, but they also demonstrate how quickly misconceptions can spread. Some commentators treat a specialist residence route as though it were the general Malta tax system.

5. Andorra

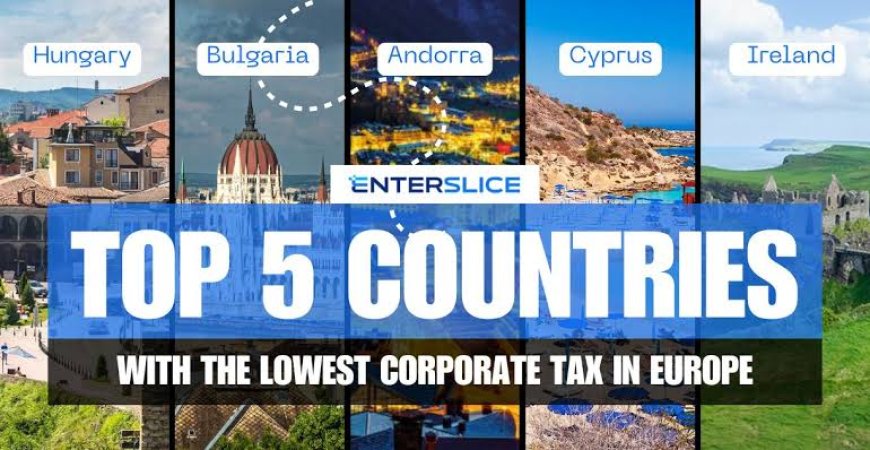
Andorra is one of the clearest examples of a European jurisdiction with relatively low personal taxation.

Its general personal income tax structure reaches a maximum rate of 10%, with lower bands applying below that level. Savings and investment income is generally subject to a 10% rate after applicable allowances.

Andorra also has a relatively low standard indirect tax rate, while its corporate income tax rate is generally 10%.

For someone researching Andorra tax residency, the lifestyle and residence requirements are just as important as the tax rate. The country is small, mountainous and closely connected to Spain and France.

Capital gains treatment also requires care. Certain disposals of shares can qualify for exemptions depending on the size of the holding, the holding period and the nature of the underlying assets. It is therefore better to describe Andorra as a jurisdiction with tax-efficient capital gains rules in qualifying cases rather than claiming that every gain is automatically tax free.

6. Bulgaria

Bulgaria is attractive in tax comparisons because of its relatively simple personal income tax structure.

A flat 10% personal income tax rate generally applies to personal income, although specific exceptions exist. Bulgarian tax residents are generally taxable on worldwide income.

Dividends are generally subject to a 5% final tax, while capital gains are generally taxed at 10%, subject to a range of exemptions.

This can make Bulgaria tax residency interesting for entrepreneurs, freelancers, investors and professionals who want a relatively straightforward EU tax system.

It is also important to remember that low income tax does not eliminate social contributions, VAT or reporting obligations.

7. Hungary

Hungary has a headline personal income tax rate of 15% for most forms of income, which keeps it firmly in conversations about European countries with low income tax.

Capital gains and dividend income are generally taxed at 15%, although additional social contribution obligations can apply depending on the type of income and the relevant limits. For employees, the social-security contribution rate is 18.5%, while employers generally pay 13% social tax.

That makes Hungary particularly interesting when comparing salary-heavy structures, but the total tax cost can be quite different from the 15% headline figure once all contributions are included.

For UK entrepreneurs moving abroad, Hungary can therefore be worth modelling rather than judging from its personal tax rate alone.

8. Romania

Romania generally applies a 10% personal income tax rate, although different rates and rules apply to certain categories of income.

The country underwent important tax changes in 2026. Dividend tax increased from 10% to 16%, while several investment-related tax rates also changed.

That change is a useful warning for anyone researching low tax countries in Europe using older comparison articles. A country can remain attractive under one measure while becoming less favourable for a particular type of income.

Romania may be relevant to professionals and business owners with straightforward income structures, but investors should pay close attention to dividends, securities gains and health insurance contributions.

9. Estonia

Estonia is different from several other low tax countries in Europe because its strongest tax advantage is often associated with corporate profit distribution rather than a very low personal income tax rate.

In 2026, Estonia's income tax rate is 22%. Its corporate tax system generally exempts undistributed profits and applies corporate tax when profits are distributed. The standard tax on distributed profits is calculated at 22/78 of the net distribution.

For a founder who wants to build a business, retain profits and reinvest capital, this can be an important feature.

Estonia is also well known for e-Residency. But this is where many online discussions become misleading. Estonian e-Residency allows access to digital business and administrative services, but it does not by itself make an individual personally tax resident in Estonia.

That distinction is critical for international business owners. A digital company registration is not the same thing as a personal relocation.

10. Portugal

Portugal needs to be included in any modern 2026 conversation about tax residency in Europe, but for different reasons from the old NHR-era articles.

Portugal's general personal income tax system is progressive. For 2026, resident rates range from 12.5% to 48%, with additional solidarity rates applying to higher levels of taxable income.

The original Non-Habitual Resident regime was repealed, subject to transitional provisions. Portugal instead uses the IFICI regime, the Tax Incentive for Scientific Research and Innovation, which is aimed at qualifying individuals performing eligible activities.

Under IFICI, qualifying employment and business or professional income can receive a special 20% rate, while certain foreign-source income can receive exemptions subject to the legislation and eligibility conditions. The regime requires the individual to have not been tax resident in Portugal during the previous five years and can apply for ten years where the requirements are met.

That means Portugal tax residency can still be attractive for the right professional profile, but it should not be marketed as a universal low-tax destination.

The Biggest Issue: Leaving UK Tax Residency Correctly

Choosing one of these tax-friendly European countries is only half of the process.

HMRC uses the Statutory Residence Test to determine whether an individual is UK resident for a tax year. The test considers days spent in the UK, automatic overseas and UK tests, and, where applicable, sufficient UK ties.

This is why simply renting an apartment abroad does not necessarily mean you have left the UK tax system.

Your family connections, available accommodation, UK work pattern, previous UK presence and overall circumstances can all matter. The exact result depends on the statutory tests rather than a universal "183-day rule".

There can also be temporary non-residence consequences. HMRC guidance confirms that, in qualifying cases, certain capital gains and income arising during a temporary period overseas can become taxable when the individual returns to the UK.

So leaving the UK for tax purposes is a structured process, not simply a change of address.

What Recent Expat Discussions Are Saying

Recent social discussions provide an interesting glimpse into what internationally mobile people are actually struggling with.

Cyprus discussions frequently focus on the practical requirements of maintaining a genuine home, employment or business connection and meeting the 60-day residence conditions.

Malta discussions increasingly focus on the distinction between its general remittance-based tax system and newer specialist residence or digital-nomad arrangements.

Broader 2026 expat discussions repeatedly return to the same point: a visa, company registration or tax identification number does not automatically settle the question of personal tax residence.

These conversations are useful for understanding real-world concerns, but they should not replace professional tax advice or the legislation itself.

Which Countries Suit Different Types of UK High Earners?

There is no universal answer because different income types create different tax outcomes.

Someone living primarily from a large investment portfolio may focus on Switzerland, Monaco, Andorra or other jurisdictions where investment gains and wealth are treated differently.

A founder receiving substantial dividends may spend more time researching Cyprus or Malta.

A business owner retaining profits for future investment may investigate Estonia's corporate tax system.

A professional working in a qualifying research, innovation or technology role may investigate Portugal's IFICI regime.

An individual looking for a relatively straightforward low headline income tax rate may examine Bulgaria, Romania, Hungary or Andorra.

That is why a good expat tax planning exercise starts with the individual rather than the country.

What UK High Earners Should Analyse Before Moving

Before committing to an international move, prepare a complete picture of your finances.

Review your salary, bonuses, dividends, investment income, pensions, property income and business interests.

Identify any planned company sale, share disposal, property sale or other major capital transaction.

Analyse your UK residence position before the move and monitor your UK day count afterwards.

Review whether your business remains centrally managed in the UK.

Consider whether you will become tax resident somewhere else under domestic law or a double taxation agreement.

Check social-security obligations separately from income tax.

Finally, keep documentary evidence of your new life abroad, including accommodation, travel records, employment or business activity, banking and other relevant evidence of genuine residence.

Final Thoughts

The landscape of Low Tax Countries in Europe has changed significantly going into 2026.

Cyprus has introduced major tax reforms, including a 15% corporate tax rate. Romania has increased its dividend tax rate to 16%. Estonia continues to distinguish retained and distributed company profits. Portugal has moved away from its historic NHR model toward a narrower incentive for scientific research and innovation. Malta continues to combine ordinary taxation with specialist remittance-based and residence frameworks.

The biggest lesson is simple: the lowest headline rate is not necessarily the lowest real tax cost for your particular situation.

For UK high earners, the most important part of international tax planning is understanding both sides of the move. You need to understand the destination country's tax regime while also making sure your UK residence position, UK-source income, business interests and future capital transactions have been considered.

A well-planned tax-efficient relocation is about compliance, timing and structure. It is not about simply finding a country with a low percentage and moving there.

For anyone researching Low Tax Countries in Europe in 2026, a personalised cross-border tax analysis should come before the relocation, not after it.

What's Your Reaction?

like

dislike

love

funny

angry

sad

wow

Lanop Business and Tax Advisors Lanop Business & Tax Advisors is a leading UK chartered accounting and tax advisory firm specialising in accounting services, tax planning, bookkeeping, payroll, VAT, corporation tax, self-assessment tax returns, business advisory, financial reporting, and cloud accounting. We support sole traders, contractors, startups, SMEs, landlords, property investors, and limited companies with tailored financial solutions that improve profitability, ensure HMRC compliance, and simplify business finances. Our chartered accountants provide proactive tax strategies, fixed-fee accounting packages, dedicated client support, and expert advice for UK and international businesses using modern accounting software including Xero and QuickBooks. Whether you need ongoing accounting support, tax optimisation, payroll management, or strategic financial guidance, Lanop delivers personalised services designed to help your business grow.