

India Used Truck Market Size, Share, Key Trends and Forecast Report 2026-2034
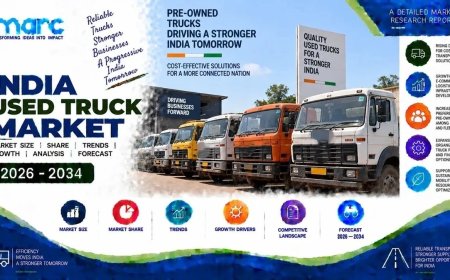
The India used truck market size was valued at USD 2.17 Billion in 2025 to USD 2.30 Billion in 2026 and is projected to reach USD 3.18 Billion by 2034, growing at a compound annual growth rate of 4.32% from 2026-2034.
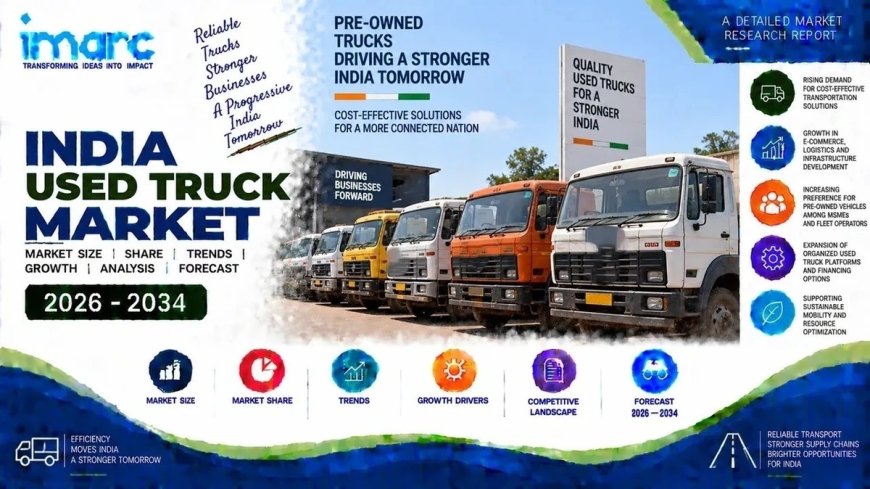
According to IMARC Group’s report titled “India Used Truck Market Size, Share, Trends and Forecast by Vehicle Type, Sales Channel, End User, and Region, 2026-2034“, the report offers a comprehensive analysis of the industry, including market share, forecast, growth and regional insights.
Market Overview & Summary
The India used truck market size was valued at USD 2.17 Billion in 2025 to USD 2.30 Billion in 2026 and is projected to reach USD 3.18 Billion by 2034, growing at a compound annual growth rate of 4.32% from 2026-2034. The structural expansion of the domestic premium retail ecosystem is driving a significant capital realignment as horological investments transition from traditional status markers into institutional wealth portfolios. For global investment authorities, brand principals, and corporate retail leaders, this evolution opens high-yield avenues within established retail structures and emerging pre-owned luxury networks.
What are the Key Developments and Emerging Shifts in the India Used Truck Market?
Vehicle Scrappage Policy: Under the Voluntary Vehicle-Fleet Modernization Program, the government provides financial incentives to phase out unfit commercial vehicles. This systematic transition encourages logistics operators to replace extremely old fleets with better-conditioned, less polluting used trucks. Consequently, the secondary market experiences an organized influx of reliable inventory, aligning commercial transport with national environmental sustainability and emission reduction objectives.
Digital Commerce Expansion: The Open Network for Digital Commerce initiative is revolutionizing retail supply chains across regional clusters. By integrating local businesses into a unified digital framework, the policy requires scalable last-mile delivery fleets. This digital transition effectively drives small transporters to procure affordable used commercial vehicles, significantly accelerating secondary market transaction volumes and improving regional economic connectivity.
Powered by Personal & Corporate Gifting: Pre-owned commercial vehicle dealerships increasingly adopt digital and NFC business cards as personal and corporate gifts to modernize networking. Aligned with the Digital India mission, utilizing these smart branded cards for employees and fleet clients enhances professional outreach. This technological transition minimizes paper usage while fostering seamless credential sharing across expansive automotive supply chains.
Infrastructure Connectivity Upgrades: The PM GatiShakti national master plan fundamentally transforms domestic freight corridors by synchronizing multi-modal transportation projects. Because enhanced highway networks facilitate faster transit times, regional logistics operators are actively expanding their operational capacities. Purchasing reliable used trucks offers a highly cost-effective strategy for transporters aiming to capitalize on these new government-backed industrial freight routes.
Formalization of Micro-Enterprises: The Udyam registration framework empowers unorganized transporters by providing formal recognition and improved access to institutional credit. This vital policy enables independent truck drivers and small fleet owners to secure affordable financing. Supported by government credit guarantee schemes, these micro-enterprises can easily procure quality used trucks, driving substantial commercial vehicle formalization across rural economies.
What Factors are Driving Growth in the India Used Truck Market?
Rural Road Connectivity: The Pradhan Mantri Gram Sadak Yojana continuously expands rural highway networks, connecting isolated agricultural hubs to mainstream commercial markets. This sustained infrastructure development necessitates dependable transportation for agricultural commodities. Because new vehicles require high capital, rural logistics providers overwhelmingly prefer affordable used trucks to transport agricultural yields efficiently along these newly paved developmental corridors.
Emission Standard Transitions: The mandated progression to BS-VI emission standards compels large institutional fleet operators to systematically rotate their older commercial vehicles. This government regulatory intervention generates a massive influx of well-maintained BS-IV trucks into the secondary marketplace. Regional transporters eagerly acquire these compliant pre-owned models, ensuring steady operational growth while maintaining overall regulatory adherence and capital efficiency.
Logistics Cost Optimization: The National Logistics Policy aims to reduce domestic supply chain costs to global benchmarks through enhanced efficiency. To achieve these competitive operational margins, medium-sized freight operators actively minimize their capital expenditures. Procuring pre-owned commercial vehicles directly aligns with this policy objective, allowing transport businesses to scale their fleet capacity while remaining highly cost-effective and profitable.
Agricultural Supply Chains: The Agriculture Infrastructure Fund provides crucial financial support for developing robust post-harvest management logistics. By empowering farmer-producer organizations to manage their own transportation, the government indirectly accelerates localized freight demand. These agricultural collectives frequently invest in pre-owned commercial trucks to transport produce from farms to specialized storage facilities, significantly boosting regional secondary vehicle sales.
Construction Sector Expansion: The National Infrastructure Pipeline allocates extensive capital toward large-scale public works, driving continuous demand for heavy construction materials. To support these government-funded building activities, contractors require substantial logistical support. Purchasing used heavy-duty trucks offers construction enterprises a practical, highly economical method to rapidly expand their material hauling capabilities without facing prohibitive initial investment costs.
➤ Request Sample Report – TOC, Charts & Key Insights: https://www.imarcgroup.com/india-used-truck-market/requestsample
Deep-Dive Segment Insights:
Vehicle Type Insights:
- Light Trucks
- Medium-duty Trucks
- Heavy-duty Trucks
Medium-duty trucks dominate with a market share of 44% of the total market in 2025.
Sales Channel Insights:
- Franchised Dealer
- Independent Dealer
- Peer-to-Peer
Franchised dealer leads with a share of 56% of the total market in 2025.
End User Insights:
- Construction
- Oil and Gas
- Others
Construction exhibits a clear dominance with a 45% share of the total market in 2025.
Regional Insights:
- South India
- North India
- West & Central India
- East India
North India dominates with a market share of 32% of the total market in 2025.
Recent Market Developments
- The Ministry of Road Transport and Highways strictly enforced robust vehicle scrappage protocols, legally mandating the immediate phase-out of archaic fleets to systematically stimulate compliant secondary commercial markets.
- The centralized Vahan portal aggressively accelerated mandatory digital registration integration, fundamentally securing immense institutional trust and drastically reducing fraudulent ownership transfers nationwide.
- The government formally streamlined GST compliance, aggressively formalizing regional dealerships.
Competitive Landscape & Key Player Positioning:
Covering an in-depth analysis of the competitive landscape, market structure, key player positioning, competitive dashboards, top winning strategies, and detailed profiles of all major industry participants you will gain access to all these exclusive insights within the full research report.
Customization Note: If you require specific data we can provide it as part of our customization services.
➤ Request Report Customization: https://www.imarcgroup.com/request?type=report&id=10084&flag=E
Frequently Asked Questions (FAQs)
1. How big is the India used truck market?
According to IMARC Group, the India used truck market size reached USD 2.17 Billion in 2025.
2. What is the expected market growth by 2034?
IMARC Group expects the market to reach USD 3.18 Billion by 2034, exhibiting a CAGR of 4.32%.
3. Which vehicle type dominates the market?
According to IMARC Group, medium-duty trucks hold the largest market share, capturing 44% of the overall market in 2025.
4. Which end user segment leads the demand?
IMARC Group states that the construction segment represents the largest end user, holding a dominant 45% market share in 2025.
5. What is the leading sales channel for used trucks?
According to IMARC Group, franchised dealers lead the sales channel segment with a 56% market share in 2025.
Strategic Insight & Verdict
The India used truck market is executing a massive structural transition heavily driven by aggressive MoRTH scrappage policies and Vahan portal digitization. As the government strictly enforces regulatory compliance and formalizes taxation, reliance on fragmented, unorganized secondary trading is permanently vanishing. For corporate stakeholders, centralized infrastructural expansion secures a highly lucrative, high-intent environment permanently optimized for organized, certified pre-owned fleet investments.
What's Your Reaction?