



United Kingdom Dairy Alternatives Market Size, Share, Trends and Report 2034
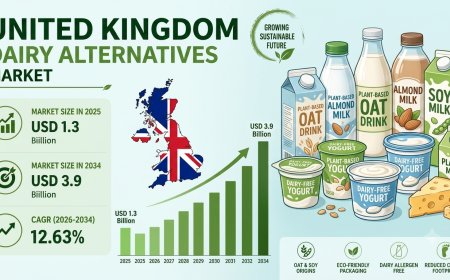
The United Kingdom dairy alternatives market size reached USD 1.3 billion in 2025 and grow at a CAGR of 12.63% to reach USD 3.9 Billion by 2034.
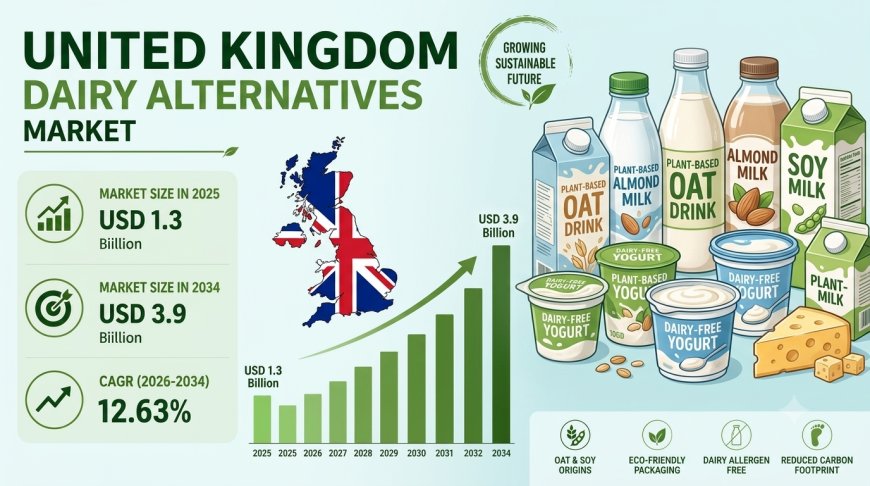
The United Kingdom dairy alternatives market is witnessing strong growth, driven by rising health awareness, the expansion of vegan and vegetarian lifestyles, growing environmental and ethical considerations, and continuous innovation in plant-based products. The market size reached USD 1.3 Billion in 2025 and is projected to reach USD 3.9 Billion by 2034, exhibiting a compound annual growth rate (CAGR) of 12.63% during 2026-2034. Concerns about lactose intolerance, allergies and cholesterol are steering consumers toward plant-based options, while advances in processing, fermentation and enzyme technology are making plant-based cheeses and yogurts increasingly similar to dairy in taste and texture. This market is strategically important to the UK food and beverage industry as it brings together established dairy brands, specialist plant-based innovators and a fast-widening base of health-conscious and sustainability-minded consumers.
The United Kingdom dairy alternatives market is poised for sustained, high-velocity expansion, with the market set to grow from USD 1.3 Billion in 2025 to USD 3.9 Billion by 2034 at a CAGR of 12.63%. Health, lifestyle, environmental and technology tailwinds present significant opportunities for established dairy leaders, plant-based specialists and new entrants focused on premium, fortified and innovative formulations.
UNITED KINGDOM DAIRY ALTERNATIVES MARKET SUMMARY
The United Kingdom dairy alternatives market encompasses plant-based substitutes for conventional dairy products, designed to deliver comparable taste, texture and nutrition for consumers seeking lactose-free, lower-saturated-fat, vegan or more sustainable options. The ecosystem includes plant-based ingredient suppliers, food and beverage manufacturers, brand owners, distributors and retailers, as well as end consumers. Major segments identified in the market include product type (cheese, creamers, yogurt, ice creams, milk and others), source (almond, soy, oats, hemp, coconut, rice and others) and distribution channel (supermarkets and hypermarkets, convenience stores, online stores and others). Dairy alternatives are widely regarded as lower in calories and saturated fat and are often fortified with vitamins and minerals such as calcium, vitamin D and B12, which supports their appeal across mainstream and functional-food consumers.
Key highlights of the market include:
• Market Size (2025): USD 1.3 Billion
• Forecast (2034): USD 3.9 Billion
• CAGR (2026-2034): 12.63%
• Historical Period: 2020-2025 | Base Year: 2025 | Forecast Period: 2026-2034
• Key Segments: Product Type, Source and Distribution Channel
• Key Regions: London, South East, North West, East of England, South West, Scotland, West Midlands, Yorkshire and The Humber, East Midlands and Others
PORTER'S FIVE FORCES ANALYSIS - UNITED KINGDOM DAIRY ALTERNATIVES MARKET
The competitive dynamics of the United Kingdom dairy alternatives market can be analyzed using Porter's Five Forces framework.
Porter's Five Forces Analysis - United Kingdom Dairy Alternatives Market
• Competitive Rivalry: Moderate to High, with established dairy companies and plant-based specialists competing through product innovation, taste and texture improvement, fortification and premium positioning. Business implication: companies that invest in R&D, differentiated formulations and strong brand building are best placed to capture share in a rapidly expanding category.
• Supplier Power: Moderate. Suppliers of key plant-based inputs such as oats, soy, almond, coconut and other sources have meaningful influence, although a diverse source base gives manufacturers room to diversify. Business implication: manufacturers should build resilient, multi-source ingredient supply chains and long-term supplier partnerships to secure quality and cost stability.
• Buyer Power: Moderate. Retailers across supermarkets, hypermarkets, convenience stores and online channels shape shelf space and listings, while consumers are increasingly informed and open to trying new products. Business implication: brands should strengthen retailer relationships, invest in omnichannel visibility and deliver strong value propositions to build loyalty.
• Threat of Substitutes: Moderate. Conventional dairy and the wide range of plant-based formats offer alternatives, but the health, lifestyle and sustainability advantages of dairy alternatives continue to widen their appeal. Business implication: clear nutritional and sustainability messaging, combined with dairy-like sensory quality, strengthens category preference.
• Threat of New Entrants: Moderate. Growing consumer demand and technology advances attract new entrants, particularly in premium and artisanal niches, while brand equity, distribution reach and R&D capability support established players. Business implication: incumbents should build defensible positions through innovation, brand strength and broad channel access.
Competitive Rivalry - Moderate to High (Healthy)
• Competition spans established dairy leaders and plant-based innovators, driving differentiation through product innovation, premium and artisanal offerings, nutritional fortification and a widening choice of plant sources rather than destructive price competition.
• Arla Foods’ plan for a plant-based version of its Lurpak butter and Else Nutrition Holdings Inc.’s launch of a plant-based complete nutrition toddler drink in the UK reflect active category expansion by both established and specialist players, strengthening the overall market ecosystem.
Request for Sample Report:
https://www.imarcgroup.com/united-kingdom-dairy-alternatives-market/requestsample
MARKET GROWTH DRIVERS: Health Awareness and Changing Dietary Lifestyles
Several key factors are propelling the expansion of the United Kingdom dairy alternatives market. Rising health awareness is a powerful demand driver, as concerns about lactose intolerance, allergies and cholesterol push consumers toward plant-based options. Dairy alternatives are widely seen as lower in calories and saturated fat and are often fortified with essential vitamins and minerals, making them attractive to health-conscious households. At the same time, the growing vegan and vegetarian movements and rising interest in functional foods are broadening the consumer base, bringing plant-based milk, yogurt, cheese, creamers and ice creams into everyday shopping baskets.
MARKET GROWTH DRIVERS: Sustainability, Ethics and Product Innovation
The United Kingdom dairy alternatives market is also benefiting from environmental and ethical considerations and accelerating technology and innovation. Consumers increasingly weigh concerns about greenhouse gas emissions, deforestation, water use, pollution and animal welfare, and sustainable, cruelty-free products resonate strongly with these buyers. Improved processing techniques, fermentation and enzyme technology are enabling plant-based cheeses and yogurts to more closely match the taste and texture of conventional dairy, while fortification with calcium, vitamin D and B12 enhances nutritional credentials. Furthermore, the growth of premium and artisanal products, such as specialty cheeses and gourmet ice creams, along with R&D investment by both established firms and new entrants, is creating fresh avenues for differentiation and value creation.
UNITED KINGDOM DAIRY ALTERNATIVES MARKET SEGMENTATION
Segmentation analysis provides a detailed view of the United Kingdom dairy alternatives market by category:
• Product Type Insights: Cheese, Creamers, Yogurt, Ice Creams, Milk, Others.
• Source Insights: Almond, Soy, Oats, Hemp, Coconut, Rice, Others.
• Distribution Channel Insights: Supermarkets and Hypermarkets, Convenience Stores, Online Stores, Others.
• Regional Insights: London, South East, North West, East of England, South West, Scotland, West Midlands, Yorkshire and The Humber, East Midlands, Others.
COMPETITIVE LANDSCAPE
The United Kingdom dairy alternatives market features a dynamic competitive landscape in which established dairy companies and specialist plant-based innovators compete through product development, premium positioning and nutritional differentiation. Companies featured in recent market developments include:
• Arla Foods
• Else Nutrition Holdings Inc.
Strategic developments are shaping the competitive arena, notably Arla Foods’ announcement of plans for a plant-based version of its Lurpak butter targeting the UK and Denmark (June 2023), and Else Nutrition Holdings Inc.’s launch of a plant-based complete nutrition toddler drink in the UK through key UK distributors, with an Amazon UK listing planned (November 2023). Detailed company profiles, market structure, player positioning, winning strategies and a competitive dashboard are covered in the full report.
REGIONAL ANALYSIS:
Regional dynamics within the United Kingdom dairy alternatives market span the major consumption centers across the country:
• London: A key demand hub where a diverse, trend-aware consumer base supports early adoption of new, premium and specialty plant-based products.
• South East: A major consumption region with strong retail presence across supermarkets, hypermarkets and online channels.
• North West: A significant regional market where widening availability of plant-based milk, yogurt and cheese supports steady uptake.
• East of England: A growing market benefiting from broad retail coverage and rising mainstream interest in plant-based diets.
• South West: A region with notable interest in sustainable and cruelty-free products, aligned with environmental and ethical purchasing motivations.
• Scotland: An important regional market with expanding access to dairy alternatives through established retail and online channels.
• West Midlands: A sizeable consumer base supporting demand across everyday categories such as milk alternatives, creamers and yogurt.
• Yorkshire and The Humber: A key regional market where health-driven choices and wider product availability contribute to growth.
• East Midlands: An emerging growth area with rising adoption of plant-based products across convenience and supermarket channels.
• Others: Remaining UK regions contribute additional demand as plant-based offerings become more widely distributed.
RECENT INDUSTRY DEVELOPMENTS
November 6, 2023: Else Nutrition Holdings Inc. launched a plant-based complete nutrition toddler drink in the UK. The product was made available through key UK distributors, with an Amazon UK listing planned.
June 12, 2023: Arla Foods announced plans for a plant-based version of its Lurpak butter, targeting the UK and Denmark, with a launch as early as the beginning of 2024.
Key Aspects Required for the United Kingdom Dairy Alternatives Market
• Market Performance: USD 1.3 Billion in 2025, with a projected trajectory to USD 3.9 Billion by 2034.
• Market Outlook: A 12.63% CAGR during 2026-2034 indicates robust, double-digit growth across cheese, creamers, yogurt, ice creams, milk and other dairy alternative categories.
• Growth Drivers: Rising health awareness around lactose intolerance, allergies and cholesterol; growing vegan and vegetarian movements and functional-food interest; environmental and ethical considerations; and technology advances in processing, fermentation and enzyme technology, alongside fortification and premium, artisanal product growth.
• Competitive Landscape: A dynamic mix of established dairy companies and plant-based specialists, with players such as Arla Foods and Else Nutrition Holdings Inc. expanding plant-based portfolios through new product launches.
• Value Chain Analysis: From sourcing of plant-based inputs (almond, soy, oats, hemp, coconut, rice and others) through processing, fortification and formulation, to branding, distribution across supermarkets, convenience stores and online channels, and final consumption.
• Industry Trends: Dairy-like taste and texture improvements in plant-based cheeses and yogurts; fortification with calcium, vitamin D and B12; premium and artisanal offerings such as specialty cheeses and gourmet ice creams; and expanding online availability.
• Strategic Recommendations: Invest in R&D and fermentation-led innovation, expand premium and fortified portfolios, diversify plant-based ingredient sources, strengthen omnichannel distribution, and align brand messaging with health, sustainability and ethical values.
Note: If you need any specific information that is not covered currently within the scope of the report, we will provide the same as a part of customization.
Request Customization: https://www.imarcgroup.com/request?type=report&id=24517&flag=E
Report Format, Delivery, and Customization Details
• Report Format Mode: PPT, PDF, and Excel
• Report Delivery Mode: Online Delivery, Physical Delivery
• Report Delivery Time: Report Delivered Over Email within 24 to 48 hours. If requested by the client, a physical copy will be delivered within three to ten days.
• Report Confirmation Mode: Yes via Email
• Report Customization Mode: Yes via Email / Call
• Report Table of Content: Yes
• Report List of Figures: Yes
• Report Methodology Mode: Yes
• Request For Sample Report: Yes
What's Your Reaction?