





GCC Data Center Market Size, Growth, and Trends Forecast 2026-2034
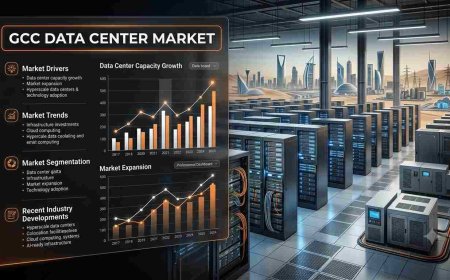
GCC data center market size was valued at USD 2.39 Billion in 2025, expected to reach USD 21.67 Billion at a CAGR of 26.78% during 2026-2034.
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the GCC Data Center Market. The GCC data center market size was valued at USD 2.39 Billion in 2025 and is projected to reach USD 21.67 Billion by 2034, exhibiting a CAGR of 26.78% during 2026-2034. Growth is being driven by accelerating cloud migration, national digitalization programs, hyperscaler entry, and surging AI workload demand across the region.
Data centers remain one of the most strategically important pieces of infrastructure for the GCC's digital transformation agenda, underpinning everything from sovereign cloud platforms and enterprise workloads to the region's rapidly scaling AI compute ambitions. As Gulf governments push ahead with national digitalization programs under Saudi Vision 2030 and UAE Centennial 2071, regional demand for colocation, hyperscale, and edge data center capacity is climbing steadily across all six member states. At the same time, global hyperscalers and government-backed entities are investing heavily in GPU clusters and liquid cooling, from Saudi Arabia's PIF-backed HUMAIN to the UAE's Stargate campus, positioning the GCC as one of the fastest-growing data center hubs in the world. Combined with strong government backing through data localization regulations and sovereign cloud partnerships, these forces are reshaping the competitive landscape and setting the stage for durable, long-term growth across the UAE, Saudi Arabia, Qatar, Kuwait, Oman, and Bahrain.
GCC Data Center Market at a Glance:
- Market Size (2025): USD 2.39 Billion
- Market Forecast (2034): USD 21.67 Billion
- Growth Rate (2026-2034): CAGR of 26.78%
- Base Year: 2025 | Historical Period: 2020-2025 | Forecast Period: 2026-2034
- Leading Size Segment: Large Data Centers, holding a 39.5% share in 2025, driven by hyperscaler and enterprise preference for consolidated, high-density facilities
- Leading Country Market: UAE, commanding a 35.2% share in 2025, anchored by Khazna's colocation build-out, Equinix's Dubai IBX facilities, and Microsoft and AWS cloud regions
How AI is Reshaping the Future of the GCC Data Center Market
- AI-Optimized Liquid Cooling Deployment: Khazna and Hewlett Packard Enterprise launched the UAE's first liquid-cooled AI data center in 2024, improving energy efficiency versus air cooling as operators retrofit and build new AI-optimized campuses to support 80-120 kW per rack density.
- HUMAIN's National AI Compute Build-Out: Saudi Arabia's PIF-backed AI company HUMAIN, launched in early 2025, announced its AI infrastructure using AMD's Instinct MI355X graphics processors and Cisco networking technology went live in September 2026, as the company targets around 6 GW of data center capacity by 2034.
- Stargate UAE and Hyperscale AI Campuses: The first 200-megawatt phase of Stargate UAE, envisioned as a one-gigawatt AI compute cluster built by G42 and operated by OpenAI and Oracle, is slated to go live in 2026, part of a wider 5 GW campus expected to cost more than USD 30 billion.
Grab a sample PDF of this report: https://www.imarcgroup.com/gcc-data-center-market/requestsample
GCC Data Center Market Trends and Drivers:
Demand for data center capacity across the GCC is being underpinned by accelerated cloud adoption and hyperscaler entry. Microsoft, Amazon Web Services, Oracle, and Google Cloud have established cloud regions in the UAE, Saudi Arabia, and Qatar since 2019, driving strong colocation demand and large-scale infrastructure investments, with AWS announcing a USD 5.3 Billion investment in 2024 to launch a new cloud region in Saudi Arabia by 2026.
The region's structural differentiator is its data localization and sovereignty regulations. Regulations such as Saudi Arabia's PDPL, the UAE's PDPL, and Qatar's data protection law mandate local data storage for sensitive information, encouraging domestic data center expansion and sovereign cloud collaborations between telecom operators and global hyperscalers across regulated sectors including BFSI and the public sector.
A third driver is surging AI, 5G, and high-performance computing demand. Rising adoption of AI and HPC workloads is increasing power density requirements in data centers, prompting upgrades such as advanced cooling systems and higher rack capacities, with GCC installed data center capacity reaching approximately 900 MW in 2025 and projected to exceed 3 GW by 2030, a dynamic that is set to intensify over the coming decade.
Government Schemes and National Digitalization Programs Driving Demand:
- Saudi Arabia's National Strategy for Data and Artificial Intelligence: Launched in 2020 and led by the Saudi Data & AI Authority under Vision 2030, NSDAI targets attracting SAR 75 Billion (approximately USD 20 Billion) in AI-related investment and hosting over 300 AI and data startups by 2030.
- HUMAIN National AI Champion: Saudi Arabia established HUMAIN in early 2025, a Public Investment Fund-majority-owned AI company with Aramco holding a significant minority stake, partnering with Qualcomm, NVIDIA, AWS, AMD, and Cisco to build a full-stack AI platform, and announcing a USD 3 Billion partnership with Blackstone-backed AirTrunk to build AI data centers in the Kingdom.
- UAE National Digitalization and Data Center Investment Commitment: The UAE's Ministry of Communications and Information Technology committed to additional investments in data centers and renewable energy amounting to USD 18 Billion by 2030, reinforcing the UAE's role as the GCC's largest data center hub by facility count.
- Data Localization and Sovereignty Regulations: Regulations including Saudi Arabia's PDPL, the UAE's PDPL, and Qatar's data protection law mandate local data storage for sensitive information, encouraging domestic data center expansion and sovereign cloud partnerships between hyperscalers and regional telecom operators.
- National Vision Programs Across the GCC: Saudi Vision 2030, UAE Centennial 2071, Qatar National Vision 2030, and Oman Vision 2040 all prioritize digital infrastructure, with consistent government spending on e-services and AI platforms driving sustained data center demand across the region.
GCC Data Center Market Industry Segmentation:
The report has segmented the market into the following categories:
Breakup By Application:
- Banking, Financial Services and Insurance (BFSI)
- Government
- IT and Telecom
- Media
- Retail
- Manufacturing
- Others
IT and Telecom leads the application segment at 38.5% share in 2025, together with BFSI and Government representing the largest application base, driven by cloud adoption, sovereign workloads, and regulated sector digital transformation.
Breakup By Type:
- Enterprise Data Centers
- Colocation Data Centers
- Edge Data Centers
- Hyperscale Data Centers
Colocation data centers lead the type segment at 42.4% share in 2025, reflecting the growing preference of enterprises and hyperscalers for wholesale, build-to-suit capacity over self-owned facilities.
Breakup By Component:
- Hardware
- Software
- Service
Hardware commands 46.3% share in 2025, reflecting heavy capex on servers, storage arrays, cooling, and power systems, while software at 28.0% is expected to grow fastest, fueled by DCIM platforms, virtualization stacks, and AI workload orchestration tools.
Breakup By Size:
- Small Data Center
- Mid-Size Data Center
- Large Data Center
Large data centers hold a 39.5% share in 2025, driven by hyperscale cloud regions, sovereign cloud facilities, and build-to-suit colocation campuses supporting AI, cloud, and enterprise workloads at scale across the UAE and Saudi Arabia.
Breakup By Country:
- Saudi Arabia
- UAE
- Qatar
- Bahrain
- Kuwait
- Oman
The UAE holds the largest country share at 35.2% in 2025, followed by Saudi Arabia at 28.0% as the fastest-growing market, while Qatar (12.0%), Kuwait (9.0%), Oman (8.0%), and Bahrain (7.8%) hold the remaining share.
Competitive Landscape:
The GCC data center market is led by a mix of global hyperscalers, regional colocation providers, and telecom-backed operators. Key players include:
- Amazon Web Services, Inc.
- Equinix, Inc.
- Microsoft
- Khazna
Khazna stands as a leading regional player, with over 350 MW of operational capacity and total capacity exceeding 600 MW in the UAE, while AWS, Microsoft, and Equinix anchor the market through cloud regions, sovereign cloud partnerships, and carrier-neutral colocation platforms across Dubai, Abu Dhabi, Muscat, and beyond.
Market Concentration Analysis:
- The GCC data center market is moderately concentrated, with the top players, Khazna, AWS, Microsoft, and Equinix, collectively accounting for approximately 55-60% of total revenue in 2025, reflecting the capital intensity of hyperscale and colocation infrastructure.
- Fragmentation increases at the mid-market and regional level, where Gulf Data Hub, MEEZA, Oman Data Park, and Batelco compete for enterprise, BFSI, and government colocation contracts, creating a tiered structure where global leaders dominate wholesale hyperscale while regional players focus on retail and sovereign niches.
- Consolidation trends are intensifying through sovereign and strategic investments, exemplified by Microsoft's USD 1.5 Billion investment in G42 and Khazna's hyperscale joint ventures, with sovereign wealth funds including PIF and Mubadala driving capacity build-out aligned with Vision 2030 and UAE Centennial 2071 priorities.
What Does The Full Report Cover?
- Historical, current, and forecast market size for the GCC data center market from 2020 to 2034
- Market breakup by application, type, component, size, and country
- Country-level analysis covering Saudi Arabia, UAE, Qatar, Bahrain, Kuwait, and Oman
- Key growth drivers, restraints, and opportunities shaping the market
- Porter's Five Forces analysis and value chain assessment
- Competitive landscape, market structure, and player positioning
- Detailed profiles of major regional and international data center operators
Recent News and Developments in the GCC Data Center Market
- October 2026: Hassan Allam Construction and Sterling & Wilson secure a SAR 750 million contract to build the first phase of the Humain-Center3 AI data centre in Riyadh, delivering 16.2 MW of IT load across four high-density halls.
- October 2026: G42’s Khazna Data Centres and Microsoft advance a 200 MW expansion in the UAE as part of a major AI and sovereign cloud partnership, with initial capacity designed to support advanced GPU workloads for public and regulated sectors.
- October 2026: UAE and Saudi Arabia accelerate large-scale AI data centre builds, including the Stargate UAE campus targeting multi-gigawatt capacity with an initial 200 MW phase, positioning the two countries to drive the majority of regional IT power growth.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
- How big is the GCC data center market and what is its growth outlook through 2034?
- What are the key growth drivers, restraints, and opportunities in the GCC data center market?
- Which application, type, component, and size segments hold the largest share of the market?
- Which country leads the GCC data center market, and why?
- How are government digitalization programs and data localization laws shaping regional demand?
- Who are the key players in the GCC data center market, and how is the competitive landscape evolving?
- What role is AI infrastructure playing in the future of GCC data center capacity build-out?
About Us
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104
What's Your Reaction?