

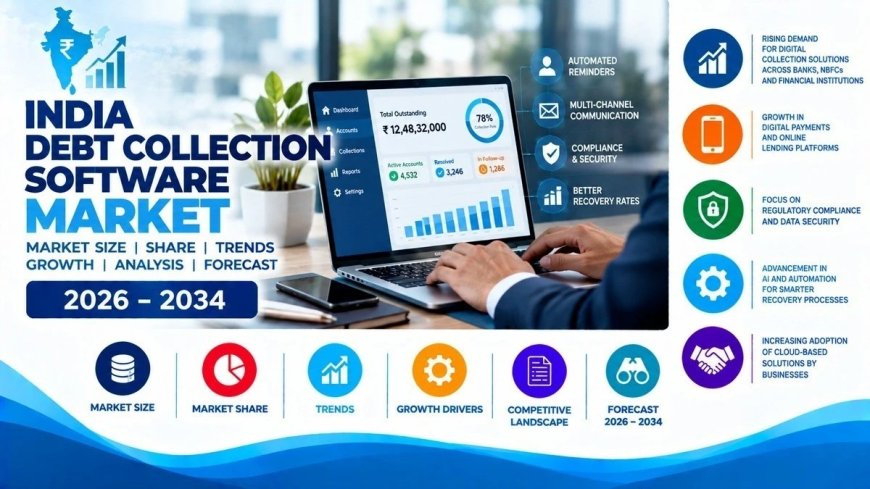
India Debt Collection Software Market Size, Share, Key Trends and Growth Outlook 2026-2034
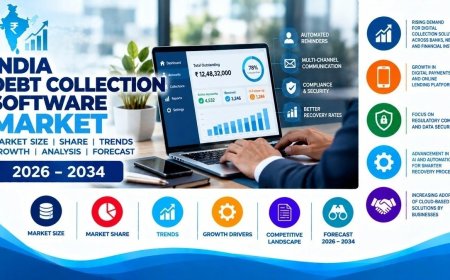
The debt collection software industry in India size reached USD 190.9 Million in 2025 to USD 220.2 Million in 2026. Looking forward, IMARC Group expects the market to reach USD 484.4 Million by 2034, exhibiting a growth rate (CAGR) of 10.35% during 2026-2034.
According to IMARC Group’s report titled “India Debt Collection Software Market Size, Share, Trends and Forecast by Component, Deployment Mode, Organization Size, End User, and Region, 2026-2034“, the report offers a comprehensive analysis of the industry, including market share, forecast, growth and regional insights.
Market Overview & Summary
The debt collection software industry in India size reached USD 190.9 Million in 2025 to USD 220.2 Million in 2026. Looking forward, IMARC Group expects the market to reach USD 484.4 Million by 2034, exhibiting a growth rate (CAGR) of 10.35% during 2026-2034. The India debt collection software market is expanding due to rising digital adoption, AI-driven automation, and regulatory compliance demands. Businesses are integrating predictive analytics, mobile-friendly interfaces, and secure data management to enhance recovery efficiency, reduce operational costs, and ensure transparency in debt collection processes.
What are the Key Developments and Emerging Shifts in the India Debt Collection Software Market?
Powered by Personal & Corporate Gifting: The fintech ecosystem is increasingly utilizing innovative networking solutions. By adopting digital and NFC business cards as personal and corporate gifts, software companies enhance client engagement. Supported by the Digital India framework, these branded smart cards empower executives to seamlessly share sophisticated debt collection software portfolios, facilitating high-value corporate outreach efficiently and sustainably nationwide.
Digitalization of Financial Services: Expanding digital connectivity has profoundly transformed banking operations. Driven by the comprehensive Digital India program, financial institutions are actively deploying advanced software for seamless debt recovery. This essential digital transition ensures real-time portfolio management, empowering rural and urban banks with instant access to professional collection tools without enduring lengthy manual processing within their core systems.
Formalization of Micro-Enterprises: Small and medium collection agencies are becoming integral to localizing the organized debt recovery supply chain. The Udyam registration portal allows regional recovery agencies to access formal credit effortlessly. This structural initiative by the Ministry of MSME empowers unorganized players to formalize operations, scale their automated collection capacities, and supply high-quality recovery services locally.
Integration of Artificial Intelligence: The continuous evolution of recovery technology demands advanced predictive analytics. Supported by national guidelines from the IndiaAI Mission, software developers are embedding artificial intelligence into collection platforms. This crucial regulatory encouragement minimizes operational inefficiencies, aligning the domestic fintech market with global technological standards to effectively capture consumer behavioral patterns and optimize debt recovery.
Data Protection and Compliance: The transition toward secure data handling is reshaping collection operations. Guided by the Digital Personal Data Protection Act frameworks under MeitY, the government actively promotes robust encryption systems within commercial software. This vital institutional support ensures the availability of secure platforms, directly elevating service quality and standardizing operational efficiency across organized collection agencies nationwide.
What Factors are Driving Growth in the India Debt Collection Software Market?
Surge in Financial Inclusion: Sustained economic advancement policies guided by the Pradhan Mantri Jan Dhan Yojana have contributed to a noticeable increase in banked populations. As credit access expands, retail lending is steadily increasing across urban and semi-urban demographics. This upward financial mobility creates widespread demand for professional, high-quality debt collection software to efficiently manage loan portfolios.
Urbanization and Retail Credit: Rapid demographic shifts require scalable financial maintenance solutions. The Smart Cities Mission directs dedicated municipal planning toward organized commercial zones. This continuous urbanization necessitates quick, reliable retail credit access. Consequently, financial institutions increasingly prefer automated debt collection software over traditional, time-consuming manual recovery methods to efficiently maintain their asset quality securely.
Expansion of Digital Lending: The exponential growth of digital commerce necessitates robust online lending networks. Acknowledging this shift, government initiatives promoting digital payment aggregators have indirectly catalyzed the fintech sector. Lenders increasingly utilize subscription-based debt collection software to execute commercial recoveries, creating a continuous and highly lucrative revenue stream for structured software developers operating and expanding nationally.
Startup Ecosystem Innovation: A robust entrepreneurial ecosystem is currently fueling innovation within the financial technology landscape. The Startup India initiative provides crucial tax exemptions to emerging digital debt collection platforms. This vital regulatory support enables new companies to develop advanced mobile-first collection applications, thereby enhancing institutional convenience and driving competitive market growth securely and sustainably nationwide.
Strengthening of NPA Management: Enhanced financial stability is directly spurring the non-performing asset management segment. Initiatives guided by the Reserve Bank of India have vastly improved loan recovery frameworks, encouraging proactive asset resolution. This institutional overhaul exposes lenders to stricter compliance requirements, thereby increasing the steady demand for specialized digital tracking and automated recovery software solutions.
➤ Request Sample Report – TOC, Charts & Key Insights: https://www.imarcgroup.com/india-debt-collection-software-market/requestsample
Deep-Dive Segment Insights:
Component Insights:
- Software
- Services
Deployment Mode Insights:
- On-Premises
- Cloud-Based
Organization Size Insights:
- Small and Medium Enterprises
- Large Enterprises
End User Insights:
- Financial Institutions
- Collection Agencies
- Healthcare
- Government
- Telecom and Utilities
- Others
Regional Insights:
- North India
- South India
- East India
- West India
Recent Market Developments
- The RBI strictly implemented enhanced digital lending guidelines, legally mandating robust algorithmic compliance within all domestic debt collection software architectures.
- The DPDP Act systematically enforced stringent data privacy protocols, directly propelling massive institutional investments in highly encrypted, compliance-driven recovery platforms.
- NPCI aggressively expanded automated UPI mandate integrations, fundamentally streamlining instantaneous, friction-free digital loan repayments across regional institutional collection networks continually.
Competitive Landscape & Key Player Positioning:
Covering an in-depth analysis of the competitive landscape, market structure, key player positioning, competitive dashboards, top winning strategies, and detailed profiles of all major industry participants you will gain access to all these exclusive insights within the full research report.
Customization Note: If you require specific data we can provide it as part of our customization services.
➤ Request Report Customization: https://www.imarcgroup.com/request?type=report&id=30572&flag=E
Frequently Asked Questions (FAQs)
1. How big is the India debt collection software market?
According to IMARC Group, the India debt collection software market size reached USD 190.9 Million in 2025.
2. What is the expected market growth by 2034?
IMARC Group expects the market to reach USD 484.4 Million by 2034, exhibiting a CAGR of 10.35%.
3. What factors are driving the India market?
IMARC Group identifies rising digital adoption, AI-driven automation, and regulatory compliance demands as primary growth drivers.
4. Which deployment mode is gaining traction?
According to IMARC Group, businesses are rapidly adopting cloud-based debt collection software for enhanced flexibility and predictive analytics.
5. Who are the major end-users in this market?
IMARC Group notes that financial institutions and collection agencies represent the largest end-user segments adopting these software solutions.
Strategic Insight & Verdict
The India debt collection software market is executing a massive structural transition fundamentally driven by RBI regulatory strictures and DPDP compliance mandates. As the government aggressively enforces fair-practice lending and UPI-driven digital recoveries, reliance on archaic, physical collection tactics is permanently vanishing. For corporate stakeholders, this highly regulated ecosystem secures a permanently lucrative environment perfectly optimized for scalable, AI-driven compliant software investments.
What's Your Reaction?