


UK Grocery Retail Market Size, Share, Trends, Growth & Analysis Report 2026-2034
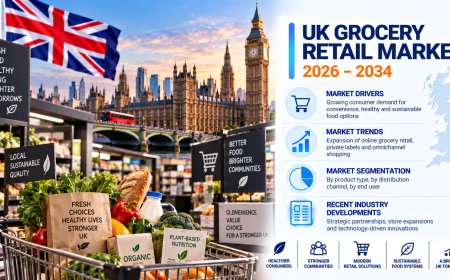
The UK grocery retail market grew from USD 300.2 Billion in 2025 to USD 307.8 Billion in 2026 and is projected to reach USD 361.1 Billion by 2034, at a CAGR of 2.02%.
Market Overview
The UK grocery retail market is advancing steadily, driven by growing adoption of digital shopping platforms, expanding private label offerings, deepening consumer preference for value and convenience, rising health consciousness, the integration of artificial intelligence across retail operations, and an increasing commitment to sustainability. The market grew from USD 300.2 Billion in 2025 to USD 307.8 Billion in 2026 and is projected to reach USD 361.1 Billion by 2034, registering a compound annual growth rate (CAGR) of 2.02% during 2026-2034. Enhanced focus on online retail channels, premium own-label ranges, and AI-driven operational efficiency are further shaping the UK grocery retail market share and outlook through 2034.
Request a Sample Report for In-Depth Market Insights: https://www.imarcgroup.com/uk-grocery-retail-market/requestsample
Market Summary
-
Rising consumer adoption of online and digital grocery shopping, supported by expanding fulfilment infrastructure including automated warehouses and click-and-collect hubs, is increasing demand for digital grocery channels and intensifying competition among retailers.
-
A competitive landscape of national supermarket chains, value-focused discounters, online specialists, and convenience operators is competing across price competitiveness, private label breadth, digital innovation, sustainability credentials, and loyalty program sophistication.
-
Rapid expansion of private label product ranges is reshaping brand loyalty dynamics, with Sainsbury's reporting in January 2026 that its premium "Taste the Difference" range recorded a 15% sales increase while broader own-brand penetration continued to gain across all grocery categories.
-
Accelerating integration of AI and digital technologies is transforming operations, with Waitrose expanding its strategic partnership with Blue Yonder in 2024 to integrate AI-driven demand forecasting tools for improved stock availability and reduced waste.
-
Growing momentum behind sustainability initiatives is influencing product sourcing and logistics, with Tesco working with more than 1,500 farmers under its Sustainable Agriculture Code and committing to a 60% reduction in direct emissions by 2025 against a 2015 baseline.
-
The market is segmented by product, distribution channel, and region for 2026-2034, with food and beverages at 81.3%, hypermarkets and supermarkets at 45.2%, and London at 16.8% in 2025.
Market Growth Drivers
Rising Consumer Adoption of Online and Digital Grocery Shopping
The growing penetration of online grocery retail across the UK is a pivotal driver of market expansion. Consumers are increasingly comfortable ordering groceries through digital platforms, mobile applications, and rapid delivery services, supported by expanding fulfilment infrastructure including automated warehouses and click-and-collect hubs. Supermarkets have invested substantially to meet this demand, extending digital capabilities from urban centers into suburban and regional markets. The ease and flexibility offered by digital grocery platforms are broadening online shopping accessibility to a larger consumer base while also motivating current users to place orders more regularly. Retailers are increasingly investing in automated fulfillment infrastructure and advanced logistics systems to improve delivery efficiency, reduce operational costs, and enhance service speed, particularly in densely populated urban markets.
Premiumization and Private Label Expansion Driving Revenue Growth
Retailers are capturing growing revenue from expanding private label programs across multiple price tiers, from entry-level value lines to premium own-brand ranges. The dominance of own-brand penetration rates in the UK grocery retail market has been achieved because of consumer demand to ensure quality at competitive prices. Premium branded products that are priced as a premium branded counterpart are doing better in their niche, such as ready meals, chilled products, and beverage shops, and this is encouraging the retailer to invest ever more in product development and packaging quality. This two-level approach helps retailers to sustain profit margins, build brand recognition, and keep those customers who may otherwise migrate to the discount stores. Investing in highly developed own brand lines, the grocery retailer can improve product differentiation, appeal to shoppers who are concerned about quality, and help to improve overall sales performance in the competitive UK grocery market.
Deployment of Artificial Intelligence Across Retail Operations
Artificial intelligence is fundamentally improving the operational efficiency and customer engagement capabilities of UK grocery retailers. Machine learning applications span demand forecasting, inventory optimization, personalized marketing, and automated checkout technologies, reducing waste, improving product availability, and enhancing the precision of promotional targeting. These capabilities contribute to stronger financial performance and greater customer satisfaction simultaneously. Retailers embedding AI into core operations are better positioned to respond to consumer behavior changes in real time, gaining a structural advantage in a highly competitive market. In 2024, Sainsbury's announced a five-year strategic partnership with Microsoft to integrate AI and machine learning capabilities into its operations, targeting sustained improvements in customer experience, store efficiency, and end-to-end supply chain performance across its entire retail network.
Porter's Five Forces Analysis
Competitive Rivalry: High
-
National supermarket chains, value-focused discounters, online specialists, and convenience operators are competing on price, private label breadth, digital innovation, and loyalty sophistication.
-
Competition spans food and beverages including fresh food, packaged food, and beverages alongside non-food items including household cleaning, personal care, and pet care products.
-
Digital capability, sustainability credentials, and data-driven personalization are key points of differentiation.
Supplier Power: Moderate to High
-
Fresh produce suppliers and agricultural producers hold influence, with approximately two-thirds of the country's fresh produce imported from the European Union.
-
Branded goods manufacturers influence shelf space allocation and promotional terms, though expanding private label ranges reduce their leverage.
-
Logistics and fulfilment providers gain importance as online and rapid delivery channels expand.
Buyer Power: High
-
Consumers can compare and switch retailers easily across hypermarkets and supermarkets, convenience stores, discount stores, and online channels.
-
Price sensitivity is high given persistent food price inflation and cost-of-living pressures, driving shoppers toward discount formats and cheaper own-label alternatives.
-
Demand for value, quality, sustainability credentials, and convenience is raising expectations for product range and service standards.
Threat of Substitutes: Moderate
-
Food service, restaurants, and takeaway providers offer substitutes for some grocery occasions, though household essentials remain core.
-
Direct-to-consumer brands and specialized online retailers provide alternatives for specific product categories.
-
Grocery retail serves essential daily consumption needs across all household segments, limiting substitution for core food and household categories.
Threat of New Entrants: Moderate
-
Rapid delivery platforms and online specialists are entering through technology-led models, with Amazon launching its Amazon Now rapid grocery delivery offering in January 2026.
-
Store network establishment, supply chain infrastructure, and scale economies raise operational barriers.
-
Established retailers with store estates, supplier relationships, and loyalty ecosystems favor incumbents, though digital-first entrants are reshaping convenience expectations.
Market Segmentation
Product Insights
-
Food and Beverages
-
Fresh Food
-
Packaged Food
-
Beverages
-
-
Non-Food Items
-
Household Cleaning Products
-
Personal Care Products
-
Pet Care Products
-
Distribution Channel Insights
-
Hypermarkets and Supermarkets
-
Convenience Stores
-
Discount Stores
-
Online
-
Others
Regional Insights
-
London
-
South East
-
North West
-
East of England
-
South West
-
Scotland
-
West Midlands
-
Yorkshire and the Humber
-
East Midlands
-
Others
Regional Analysis
London: London leads the UK grocery retail market at 16.8% in 2025, underpinned by its population density, high average household incomes, and concentration of both premium grocery formats and discount outlets. The capital hosts the broadest diversity of retail formats, from luxury food halls and convenience stores to full-service supermarkets and dark stores supporting rapid online delivery. Its multicultural consumer base drives demand for international food categories, specialty ingredients, and ready-to-eat options less prevalent in smaller regional markets. London's grocery retail environment is strongly influenced by growing online shopping and rapid delivery services, with the city's large population of busy professionals and commuters creating strong demand for convenient grocery options including ready-to-eat meals, meal kits, and flexible home delivery. Retailers maintain extensive store networks across the capital serving both in-store shoppers and online order fulfillment, with these physical outlets also functioning as key logistics and distribution points supporting digital grocery operations.
South East: The South East has a substantial grocery retail market, supported by high household incomes, residential property values, and an extensive commuter population. Demand spans premium formats, convenience stores, and online channels, with the region benefiting from proximity to London and established distribution infrastructure supporting omnichannel operations.
North West: The North West ranks among the higher-demand regions, supported by major urban centres including Manchester and Liverpool, diverse demographics, and growing discount store presence. Value-focused formats and convenience channels serve price-sensitive consumers alongside full-service supermarkets.
East of England: The East of England has mid-range demand, with growing suburban populations, agricultural production, and improving retail accessibility supporting grocery retail across urban and rural areas.
South West: The South West has a growing grocery retail market, supported by tourism activity, residential communities, and expanding online delivery coverage. Regional retailers and national chains serve diverse consumer segments across coastal and rural areas.
Scotland: Scotland's grocery retail market is supported by national supermarket chains, convenience operators, and growing discount store presence. The region's distinct regulatory environment and rural geography support demand for both in-store and online grocery channels.
West Midlands: The West Midlands has a significant grocery retail market, supported by urban centres including Birmingham, diverse demographics, and expanding discount and convenience formats serving price-sensitive consumers.
Yorkshire and the Humber: Yorkshire and the Humber has demand around the national average, with large urban centres including Leeds and Sheffield supporting demand across supermarkets, discounters, and online channels.
East Midlands: The East Midlands has mid-range demand, with commuter and logistics activity supporting grocery retail across supermarkets, convenience stores, and online channels.
Others: Other regions, including Wales and Northern Ireland, generally see lower-to-mid demand, although national chains, discounters, and expanding online delivery are widening access to grocery retail across diverse communities.
Competitive Landscape
The UK grocery retail market is characterized by intense competition among a diverse mix of national supermarket chains, value-focused discounters, online specialists, and convenience operators. Retailers are competing across multiple dimensions, including price competitiveness, private label breadth, digital innovation, sustainability credentials, and loyalty program sophistication. Discounters continue to gain share through store network expansion and quality improvements, while established supermarket leaders defend their positions through data-driven personalization and omnichannel investment. Consolidation trends and strategic format diversification are reshaping the competitive landscape, compelling all market participants to continuously refine their customer value propositions in response to evolving shopper expectations.
Key players include:
-
Sainsbury's
-
Tesco
-
Waitrose
-
Amazon
-
National supermarket chains, discounters, online specialists, and convenience operators
Recent Industry Developments
November 2026: UK supermarket sales strengthened in October, with total till sales at major grocery retailers increasing by 3.2% during the four weeks ending 31 October, according to NielsenIQ. Unit sales rose 1.5%, while online grocery sales increased 13.1%, compared with 1.5% growth in physical stores. E-commerce accounted for nearly 59% of total value growth and 80% of incremental unit growth. Ocado recorded 16.8% sales growth over 12 weeks, followed by M&S at 10.9% and Lidl at 6.7%. The results highlight the growing importance of online channels, convenience, and value-oriented shopping.
November 2026: Lidl reported that its premium private-label Deluxe range generated £1.07 billion in sales during the year to September 2026, representing 12% year-on-year growth and an increase of £100 million. More than half of British households and three-quarters of shoppers reportedly purchased products from the range. The retailer is expanding its premium assortment with more than 130 new products for the Christmas season, highlighting the growing appeal of affordable premium grocery products.
November 2026: Marks & Spencer reported strong first-half performance for 2026/27, with total sales increasing 16.2% to £9.2 billion. Food sales grew 13.9%, supported by product innovation, store investment, and online distribution through Ocado Retail, where M&S food sales increased 22.8%. The results underline the growing contribution of premium food ranges and digital grocery partnerships to supermarket performance.
Key Aspects Required for the UK Grocery Retail Market
-
Market Performance: The market grew from USD 300.2 Billion in 2025 to USD 307.8 Billion in 2026 and is projected to reach USD 361.1 Billion by 2034, driven by digital shopping adoption, private label expansion, AI integration, and sustainability commitments.
-
Market Outlook: A 2.02% CAGR during 2026-2034 reflects steady expansion supported by online retail channel development, digital innovation, private label growth, and competitive pricing strategies.
-
Growth Drivers: Rising consumer adoption of online and digital grocery shopping; premiumization and private label expansion driving revenue growth; and deployment of artificial intelligence across retail operations, together shaping long-term demand.
-
Competitive Landscape: Sainsbury's, Tesco, Waitrose, and Amazon alongside national supermarket chains, discounters, online specialists, and convenience operators are competing on price, private label breadth, digital innovation, and sustainability credentials.
-
Value Chain Analysis: The value chain runs from fresh produce and branded goods suppliers through national supermarket chains, discounters, convenience operators, and online platforms to households across UK regions, supported by fulfilment infrastructure, automated warehouses, click-and-collect hubs, and loyalty ecosystems.
-
Industry Trends: Rapid expansion of private label product ranges across premium and value tiers; accelerating integration of AI and digital technologies for demand forecasting and personalization; and growing momentum behind sustainability initiatives including carbon reduction and regenerative farming partnerships.
-
Strategic Recommendations: Invest in automated fulfilment infrastructure and digital platforms to capture online grocery growth; expand premium and value-tier private label ranges to strengthen margins and brand loyalty; deploy AI-driven demand forecasting and personalization capabilities; and deepen sustainability commitments through supplier engagement and emissions reduction programs.
Note: If you need any specific information that is not currently covered within the scope of the report, we will provide the same as a part of customization.
Speak to an analyst: https://www.imarcgroup.com/request?type=report&id=25408&flag=C
Frequently Asked Questions
1. What is the size of the UK grocery retail market?
The market increased from USD 300.2 Billion in 2025 to USD 307.8 Billion in 2026 and is projected to reach USD 361.1 Billion by 2034.
2. What is the expected growth rate of the UK grocery retail market?
The market is projected to grow at a CAGR of 2.02% during 2026-2034.
3. What is driving the growth of the UK grocery retail market?
Growth is driven by rising online grocery adoption, accelerating integration of AI and digital technologies, expanding private label product ranges, growing sustainability initiatives, and increasing consumer demand for convenience and value-oriented shopping experiences across diverse retail formats.
What's Your Reaction?