


Europe Organic Food Market 2026 | Worth USD 139.4 Billion by 2034
Europe organic food market to grow from USD 70.3B in 2026 to USD 139.4B by 2034, driven by health awareness and sustainable food demand.
Market Overview
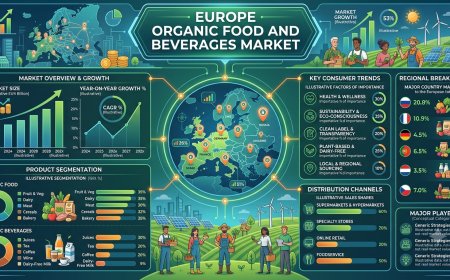
The Europe organic food market grew from USD 63.1 Billion in 2025 to USD 70.3 Billion in 2026 and is projected to reach USD 139.4 Billion by 2034, growing at a CAGR of 8.94% during 2026-2034. Rising consumer demand for sustainable products, heightened health consciousness, supportive EU regulatory frameworks, and the mainstreaming of organic food across major retail channels are key growth drivers.
Organic food encompasses agricultural goods cultivated and processed without synthetic fertilizers, pesticides, artificial additives, or genetically modified organisms. The Europe organic food market encompasses organic fruits and vegetables, organic meat, poultry and dairy, organic processed food, organic bread and bakery, organic beverages, organic cereal and food grains, and other product types, distributed through supermarkets and hypermarkets, specialty stores, convenience stores, online stores, and other channels, serving applications across bakery and confectionery, ready-to-eat food products, breakfast cereals, and others in Germany, France, United Kingdom, Italy, Spain, and other European countries. The European organic food market ecosystem spans certified organic farmers, processing and manufacturing facilities, certification bodies, wholesale distributors, specialist organic retailers, mainstream grocery chains, and e-commerce platforms. Europe has long been the global leader in organic food consumption, supported by a dense regulatory framework anchored in EU Regulation 2018/848, which entered full effect in 2022, establishing comprehensive standards for organic production, labeling, and controls across all member states. Macroeconomic factors driving the market include rising per capita disposable incomes, growing urbanization, increasing awareness of the health consequences of pesticide-laden conventional diets, and policy alignment with the European Green Deal and Farm to Fork Strategy, which aims to have at least 25% of EU agricultural land under organic farming by 2030.
This market is strategically important to Europe's food security and sustainability agenda, supporting the region's position as a global leader in organic farming and consumption. Germany dominates, holding a 22.4% market share in 2025, while organic fruits and vegetables lead product type demand at 28.8%. Supermarkets and hypermarkets remain the dominant distribution channel with a 44.0% share. Organic food offers consumers a credible pathway to healthier, chemical-free nutrition while aligning with broader sustainability values, making it a preferred choice across European households, food service operators, and institutional buyers. With product categories spanning organic produce, dairy, meat, beverages, cereals, and processed foods, the market is expected to continue expanding, supported by innovations in organic farming technology, expansion of certified supply chains, and increasing mainstream retail and e-commerce penetration across all European sub-markets.
The Europe organic food market is poised for sustained expansion, underpinned by increasing consumer preference for plant-based organic foods, rising e-commerce penetration in organic food distribution, product innovation and diversification, and premiumization and private label expansion. With a projected CAGR of 8.94% through 2034, the market presents significant opportunities for providers focusing on organic plant-based beverages, functional foods, direct-to-consumer digital platforms, Eastern European market expansion, blockchain-based traceability, sustainable packaging, and organic farming conversion financing.
EUROPE ORGANIC FOOD MARKET SUMMARY
The Europe organic food market encompasses the production, processing, certification, distribution, and retail of agricultural goods cultivated and processed without synthetic fertilizers, pesticides, artificial additives, or genetically modified organisms, serving health-conscious consumers, foodservice operators, and institutional buyers across the region.
The ecosystem spans certified organic farmers, processing and manufacturing facilities, certification bodies (ECOCERT, Soil Association), wholesale distributors, specialist organic retailers, mainstream grocery chains, and e-commerce platforms serving customers across residential, commercial, and institutional sectors throughout Europe .
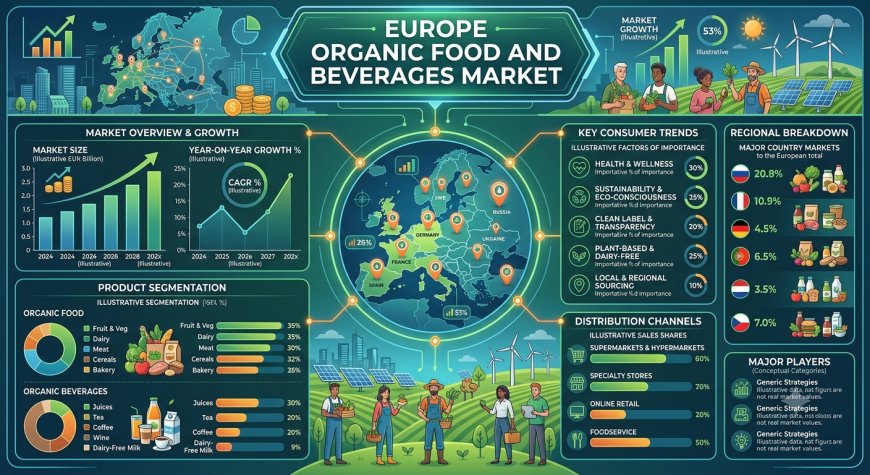
By Product Type, the market is segmented into Organic Fruits and Vegetables (dominating at 28.8%), Organic Meat, Poultry and Dairy (18.6%), Organic Processed Food (14.2%), Organic Bread and Bakery, Organic Beverages (12.4%), Organic Cereal and Food Grains, and Others.
By Distribution Channel, the market serves Supermarkets and Hypermarkets (dominating at 44.0%), Specialty Stores (23.5%), Convenience Stores, Online Stores (17.6%), and Others.
By Application, the market serves Bakery and Confectionery, Ready-to-eat Food Products, Breakfast Cereals, and Others.
By Country, the market serves Germany (dominating at 22.4%), France (18.9%), United Kingdom (16.5%), Italy (14.8%), Spain (13.6%), and Others (13.8%).
Key trends shaping the market include increasing consumer preference for plant-based organic foods, rising e-commerce penetration in organic food distribution, product innovation and diversification, premiumization and private label expansion, and blockchain-based supply chain traceability.
PORTER'S FIVE FORCES ANALYSIS – EUROPE ORGANIC FOOD MARKET
Competitive Rivalry: Moderate. The market exhibits a moderately fragmented competitive structure, with the top five participants collectively holding approximately 22–26% of European organic food retail revenue in 2025. Competition centres on certification credibility, price positioning, product innovation, sustainability credentials, and distribution reach. Specialist organic chains, retailer-owned private-label brands, and regional organic cooperatives account for the balance, ensuring a diverse and competitive landscape. Business implication: Companies must differentiate through certification authenticity, sustainable packaging, and omnichannel distribution capability.
Supplier Power (Certified Organic Farmers and Producers): Moderate. Manufacturers and retailers rely on certified organic farmers and producers. Maintaining organic certification across complex, multi-country European supply chains involves significant administrative and financial burden. Smallholder producers face disproportionate certification costs that constrain supply-side scalability. Climate variability and yield uncertainty introduce supply-side volatility. Business implication: Strategic partnerships with certified organic cooperatives and investment in organic farming conversion financing can reduce long-term dependency and supply risk.
Buyer Power (Retailers and Consumers): Moderate to High. Major grocery retailers, e-commerce platforms, and consumers leverage choice across multiple brands and distribution channels. Buyers increasingly demand certification transparency, sustainable packaging, and competitive pricing. Retailers leverage volume purchasing power to negotiate favourable terms with organic producers. Business implication: Providers must demonstrate verifiable certification, supply chain traceability, and alignment with buyer sustainability objectives.
Threat of Substitutes: Moderate. Conventional food products, non-organic premium foods, and locally sourced conventional produce represent substitutes. However, organic food offers health, environmental, and ethical value propositions that conventional alternatives cannot fully replicate. Price premiums of 50-75% over conventional products limit mass-market penetration in some segments. Business implication: Demonstrating superior health benefits, environmental credentials, and value for money is essential.
Threat of New Entrants: Moderate. Significant capital requirements for certification, organic farming conversion (2-3 year transition), and distribution networks create barriers. However, growth of e-commerce platforms, direct-to-consumer models, and organic private label expansion has enabled new entrants focused on niche categories and digital-first business models. Business implication: Incumbents must leverage scale, certification heritage, and retail relationships while monitoring emerging niche players.
KEY ASPECTS REQUIRED FOR THE EUROPE ORGANIC FOOD MARKET
Market Performance: USD 63.1 Billion in 2025, projected to reach USD 139.4 Billion by 2034, driven by rising health consciousness, supportive EU regulatory frameworks, and mainstreaming of organic food across retail channels.
Market Outlook: A 8.94% CAGR through 2034 reflects strong growth led by organic fruits and vegetables, supermarkets and hypermarkets, and German market dominance.
Growth Drivers: Rising health and wellness consciousness; supportive EU regulatory framework (EU Regulation 2018/848 and Farm to Fork Strategy); expansion of organic retail infrastructure; growth of plant-based and functional food demand; e-commerce and direct-to-consumer expansion; organic private label growth; emerging demand in Eastern Europe; increasing consumer preference for plant-based organic foods; rising e-commerce penetration; product innovation and diversification; premiumization and private label expansion.
Competitive Landscape: A moderately fragmented market with specialist organic chains, retailer-owned private-label brands, and regional organic cooperatives. Key players invest in sustainable packaging, blockchain-based traceability, and product innovation.
Value Chain Analysis: From organic farming through processing and manufacturing, certification and compliance, packaging and labeling, distribution and logistics, retail and e-commerce, to end consumers across health-conscious households, foodservice operators, and institutional buyers.
Industry Trends: Increasing consumer preference for plant-based organic foods (Delicious project); rising e-commerce penetration; product innovation and diversification (organic beverages, recyclable packaging); premiumization and private label expansion (Alnatura organic pasture milk); blockchain-based supply chain traceability; precision organic farming technology; sustainable packaging innovation.
Strategic Recommendations: Invest in e-commerce and direct-to-consumer platforms; develop organic private label ranges; expand into Eastern European markets; pursue blockchain-based traceability technology; develop sustainable packaging solutions; target organic plant-based beverages and functional foods; strengthen presence in Germany and high-growth markets; pursue organic farming conversion financing; invest in precision organic farming technology.
Request for Sample Report: https://www.imarcgroup.com/europe-organic-food-market/requestsample
MARKET GROWTH DRIVERS
Rising Health and Wellness Consciousness
Consumer awareness of the health risks associated with synthetic pesticides, chemical preservatives, and GMO ingredients is accelerating the structural shift toward certified organic food products across all European demographic segments. There is a growing understanding of the connection between diet and long-term health outcomes, leading to increased demand for chemical-free, nutrient-dense food options. This trend drives the adoption of organic food products across all age groups and income levels. Additionally, the increasing prevalence of food allergies, intolerances, and lifestyle-related health conditions is prompting consumers to seek cleaner, more natural food alternatives. Companies in the organic food market are actively investing in product innovation, certification transparency, and educational marketing to meet the evolving demands of health-conscious consumers.
Supportive EU Regulatory Framework
The implementation of EU Regulation 2018/848 and the Farm to Fork Strategy, committing to 25% organic agricultural land by 2030, provides enduring structural demand support. The European Green Deal and its associated policies create a favorable environment for organic food production and consumption. Additionally, government subsidies and incentives for organic farming conversion are encouraging producers to transition from conventional to organic practices. The regulatory framework ensures consistent standards for organic production, labeling, and controls across all member states, building consumer trust and facilitating cross-border trade. These regulatory initiatives are further bolstering the market growth in the region.
Expansion of Organic Retail Infrastructure
The proliferation of dedicated organic aisles within mainstream supermarket chains, alongside rapid growth of specialty organic retail formats and e-commerce platforms, has dramatically increased product accessibility across European consumer income brackets. Moreover, numerous factors such as changing consumer preferences, convenience, and the growth of online shopping are positively influencing the market growth. Apart from this, the implementation of digital platforms and subscription-based delivery models connecting producers to end buyers is another major growth-inducing factor. Additionally, the rising availability of various e-commerce platforms and solutions to meet the diverse needs of different consumers is propelling the market growth. Furthermore, e-commerce enables the efficient and safe delivery of organic food products to consumers while preserving their quality and providing convenience.
Growth of Plant-Based and Functional Food Demand
Accelerating adoption of plant-based diets across Europe, combined with growing interest in functional foods enriched with vitamins, probiotics, and adaptogens, has significantly expanded the addressable market for organic food producers, creating powerful cross-category demand synergies. In December 2024, the European innovation project Delicious, backed by Horizon Europe with EUR 5 million, launched in Barcelona to revolutionize plant-based dairy using microbial fermentation and machine learning for sustainable, nutritious alternatives. Aligned with a plant-based food market projected to reach €40 billion by 2027, the initiative aims to cut dairy production emissions by up to 30% while accelerating the shift toward sustainable diets in Europe. This convergence of plant-based and organic trends is driving significant market growth.
Product Innovation and Premiumization
Organic beverages, including cold-pressed juices, kombucha, botanical waters, and plant-based milk alternatives, have posted strong growth. In September 2024, Marigold Health Foods and Sonoco introduced a fully recyclable can composed of 95% paper and 60% recycled fiber, setting a new benchmark for sustainable organic food packaging. This commitment to continuous innovation drives both new consumer acquisition and retention, supporting sustained market growth. Major European grocery retailers are also expanding their private-label organic ranges, bringing certified organic products within reach of mainstream shoppers at significantly reduced price premiums compared to branded alternatives. In February 2024, Alnatura announced the launch of a complete range of organic pasture milk products, including cream fraiche, yogurt, and fresh milk, with expansion planned to over 30 products, setting a new commercial benchmark for organic dairy quality standards in Germany.
EUROPE ORGANIC FOOD MARKET SEGMENTATION
Segmentation analysis provides a detailed view of the Europe organic food market by category:
Product Type Insights: Organic fruits and vegetables dominate the product type segment with a 28.8% share in 2025. This leading position reflects the category's long-established consumer appeal as the most intuitive entry point into organic food purchasing, strongly supported by widespread awareness of pesticide residue risks in conventionally farmed produce and the accelerating adoption of plant-based dietary patterns across European markets. Organic meat, poultry, and dairy holds 18.6%, driven by consumer concern over antibiotic use and animal welfare in conventional livestock production. Organic processed food accounts for 14.2%, growing as manufacturers reformulate mainstream convenience products with organic-certified ingredients. Organic beverages (12.4%) are among the fastest-growing sub-segments, with cold-pressed juices, kombucha, and plant-based milk driving premium consumption occasions. Organic bread and bakery, organic cereal and food grains, and other product types represent significant segments with growing demand.
Distribution Channel Insights: Supermarkets and hypermarkets lead distribution with a commanding 44.0% share in 2025. This dominance reflects strategic decisions by Europe's largest grocery retailers to position organic food as a mainstream category, through expanded organic assortments, private-label organic ranges at competitive price points, and prominent in-store positioning. Specialty stores represent the second-largest channel at 23.5%, serving the most engaged organic consumer segment that prioritizes product provenance, certification transparency, and specialist product knowledge. Online stores have grown to 17.6% of distribution, driven by accelerating e-commerce adoption post-pandemic and the emergence of specialist organic delivery platforms and subscription box services that offer curated organic assortments with doorstep delivery. Convenience stores and other distribution channels represent significant segments with growing demand.
Application Insights: The report has provided a detailed breakup and analysis of the market based on the application. This includes bakery and confectionery, ready-to-eat food products, breakfast cereals, and others. Organic bakery and confectionery products are gaining popularity as consumers seek healthier indulgence options made with organic ingredients. Ready-to-eat organic food products are experiencing strong growth, driven by busy lifestyles and increasing demand for convenient, healthy meal solutions. Organic breakfast cereals represent a significant segment, appealing to health-conscious consumers seeking nutritious morning meal options. Other applications including organic baby food, organic snacks, and organic pet food represent growing segments with increasing consumer demand.
Country Insights: Germany's market leadership (22.4%, 2025) reflects decades of investment in organic farming infrastructure, a highly developed certification ecosystem, and one of the highest per-capita organic food expenditure rates globally. Organic sales in the country reached a record EUR 17 billion (USD 20.14 billion) in 2024, marking a 5.7% increase compared to the previous year. France (18.9%) has undergone one of the fastest organic farming expansion trajectories in Europe, supported by the Ambition Bio 2027 plan with 27 measures to boost organic production and consumption, targeting 18% of farmland under organic cultivation by 2027. The United Kingdom (16.5%) has maintained strong momentum despite post-Brexit regulatory divergence, supported by Soil Association recognition and accelerating online organic grocery adoption. Italy (14.8%) has the largest EU organic farmland area and a strong agri-food heritage. Spain (13.6%) has the largest organic area by hectare and rising domestic demand. Others (13.8%) include Netherlands, Switzerland, Austria, and Poland with rising organic consumption.
COMPETITIVE LANDSCAPE
The Europe organic food market exhibits a moderately fragmented competitive structure. The top five participants, Alnatura Produktions- und Handels GmbH, REWE Group, Carrefour, Windmill Organics, and dm-drogerie markt GmbH + Co. KG, collectively hold approximately 22–26% of European organic food retail revenue in 2025. Specialist organic chains, retailer-owned private-label brands, and regional organic cooperatives account for the balance, ensuring a diverse and competitive landscape across product categories and geographies. Market consolidation is gradually accelerating as large food and beverage groups acquire established organic brands to quickly access certified supply chains, loyal consumer bases, and premium category positioning. E-commerce has meaningfully disrupted traditional competitive dynamics by enabling smaller organic producers to access pan-European consumer audiences without requiring large-scale retail distribution agreements.
Major players include Alnatura Produktions- und Handels GmbH, REWE Group, Carrefour, Windmill Organics, dm-drogerie markt GmbH + Co. KG, Waitrose & Partners, and others investing in sustainable packaging, blockchain-based traceability, and product innovation.
Recent Developments:
February 2024: Alnatura became the first brand to offer a complete range of organic pasture milk products from a single source, expanding from six products to over 30 by mid-2024.
September 2024: Marigold Health Foods and Sonoco introduced a fully recyclable can composed of 95% paper and 60% recycled fiber.
September 2024: Biona, a brand under Windmill Organics, launched its Organic Super Seed Bread, a protein-rich sliced loaf containing sunflower, flax, and pumpkin seeds.
December 2024: The European innovation project Delicious, backed by Horizon Europe with EUR 5 million, launched in Barcelona to revolutionize plant-based dairy.
December 2025: REWE partnered with Bioland, Germany's largest organic farming association, to expand its range of certified organic products.
Investment opportunities exist in organic plant-based beverages, functional foods, direct-to-consumer digital platforms, Eastern European market expansion, blockchain-based traceability technology, sustainable packaging innovation, and organic farming conversion financing.
REGIONAL ANALYSIS
Germany's market leadership (22.4%, 2025) reflects decades of investment in organic farming infrastructure, a highly developed certification ecosystem, and one of the highest per-capita organic food expenditure rates globally. Organic sales in the country reached a record EUR 17 billion (USD 20.14 billion) in 2024, marking a 5.7% increase compared to the previous year. Germany holds 22.4% of the European organic food market in 2025, supported by an advanced certification ecosystem, approximately 35,881 farms operating under organic farming standards, and one of Europe's highest per-capita organic food expenditure rates.
France (18.9%) has undergone one of the fastest organic farming expansion trajectories in Europe, supported by the Ambition Bio 2027 plan with 27 measures to boost organic production and consumption, targeting 18% of farmland under organic cultivation by 2027. The country's local sourcing preference and agri-tourism sector support substantial organic food demand.
The United Kingdom (16.5%) has maintained strong momentum despite post-Brexit regulatory divergence, supported by Soil Association recognition and accelerating online organic grocery adoption. The country's post-Brexit sustainability focus and growing online organic grocery channels create substantial organic food demand.
Italy (14.8%) has the largest EU organic farmland area, a strong agri-food heritage, and a thriving tourism sector driving organic food demand. Spain (13.6%) is emerging as a faster-growing market, driven by its status as Europe's largest organic agricultural area by hectare and rapidly increasing domestic organic consumption alongside its traditionally export-oriented model. Spain is emerging as the fastest-growing country, driven by organic farmland expansion and domestic demand growth.
Others (13.8%) include Netherlands, Switzerland, Austria, and Poland, which collectively contribute to the market with rising organic consumption. Eastern European countries represent significant untapped growth opportunities, as rising incomes and growing health awareness align with the well-established Western European organic consumption model.
RECENT INDUSTRY DEVELOPMENTS
2026 Activity: The Europe organic food market continued its growth trajectory from USD 63.1 Billion in 2025 to USD 70.3 Billion in 2026 toward USD 139.4 Billion by 2034 at a CAGR of 8.94%.
February 2024: Alnatura became the first brand to offer a complete range of organic pasture milk products from a single source, expanding from six products to over 30 by mid-2024.
September 2024: Marigold Health Foods and Sonoco introduced a fully recyclable can composed of 95% paper and 60% recycled fiber, setting a new benchmark for sustainable organic food packaging.
September 2024: Biona launched its Organic Super Seed Bread, a protein-rich sliced loaf containing sunflower, flax, and pumpkin seeds.
December 2024: The European innovation project Delicious launched in Barcelona to revolutionize plant-based dairy using microbial fermentation and machine learning.
December 2025: REWE partnered with Bioland to expand its range of certified organic products, particularly locally sourced fresh items.
FREQUENTLY ASKED QUESTIONS
Q1: What is the current size of the Europe organic food market?
A: The Europe organic food market grew from USD 63.1 Billion in 2025 to USD 70.3 Billion in 2026 and is projected to reach USD 139.4 Billion by 2034, exhibiting a CAGR of 8.94% from 2026-2034.
Q2: What are the key drivers of the Europe organic food market?
A: The market is driven by: (i) rising health and wellness consciousness; (ii) supportive EU regulatory framework (EU Regulation 2018/848 and Farm to Fork Strategy); (iii) expansion of organic retail infrastructure; (iv) growth of plant-based and functional food demand; (v) e-commerce and direct-to-consumer expansion; (vi) organic private label growth; (vii) emerging demand in Eastern Europe; (viii) increasing consumer preference for plant-based organic foods; (ix) rising e-commerce penetration; (x) product innovation and diversification; and (xi) premiumization and private label expansion.
Q3: What are the major product types in the Europe organic food market?
A: Major product types include Organic Fruits and Vegetables (dominating at 28.8%), Organic Meat, Poultry and Dairy (18.6%), Organic Processed Food (14.2%), Organic Bread and Bakery, Organic Beverages (12.4%), Organic Cereal and Food Grains, and Others.
Q4: What are the major distribution channels in the Europe organic food market?
A: Major distribution channels include Supermarkets and Hypermarkets (dominating at 44.0%), Specialty Stores (23.5%), Convenience Stores, Online Stores (17.6%), and Others.
Q5: What are the major applications in the Europe organic food market?
A: Major applications include Bakery and Confectionery, Ready-to-eat Food Products, Breakfast Cereals, and Others.
Q6: Which country leads the Europe organic food market?
A: Germany dominates the Europe organic food market with a 22.4% share in 2025, driven by its established organic culture, advanced certification ecosystem, government farm subsidies, and one of Europe's highest per-capita organic food expenditure rates. France (18.9%) and United Kingdom (16.5%) follow. Spain is the fastest-growing country.
Q7: What are the challenges facing the Europe organic food market?
A: Key challenges include price premium over conventional products (50-75% higher), supply chain fragmentation and certification complexity, consumer skepticism and greenwashing concerns, climate variability and yield uncertainty, and regulatory divergence post-Brexit creating dual compliance requirements.
Q8: What is the outlook for the Europe organic food market?
A: The market is projected to grow at a 8.94% CAGR through 2034, with growth driven by regulatory evolution, growing health consciousness, and the continued mainstreaming of organic food. The shift toward organic plant-based beverages, functional foods, blockchain-based traceability, and sustainable packaging are expected to shape the market's evolution.
Q9: Who are the key players in the Europe organic food market?
A: Key players include Alnatura Produktions- und Handels GmbH, REWE Group, Carrefour, Windmill Organics, dm-drogerie markt GmbH + Co. KG, Waitrose & Partners, and others.
Note: If you need any specific information that is not covered currently within the scope of the report, we will provide the same as a part of customization.
https://www.imarcgroup.com/request?type=report&id=8933&flag=E
Report Format, Delivery, and Customization Details
Report Format Mode: PPT, PDF, and Excel
Report Delivery Mode: Online Delivery, Physical Delivery
Report Delivery Time: Report Delivered Over Email within 24 to 48 hours. If requested by the client, a physical copy will be delivered within three to ten days.
Report Confirmation Mode: Yes via Email
Report Customization Mode: Yes via Email / Call
Report Table of Content: Yes
Report List of Figures: Yes
Report Methodology Mode: Yes
Request For Sample Report: Yes
What's Your Reaction?